When a company sells an investment property, a shareholding or another capital asset for more than it cost, the profit is a chargeable gain. Companies do not pay Capital Gains Tax: the gain is added to their other profits and taxed as Corporation Tax at the same rate. This guide shows how to record disposals on the Chargeable Gains tab, how capital losses are used, and where everything lands on the CT600.
How a company is taxed on a gain
For each disposal the gain is worked out as:
- Proceeds — what the company received, or market value if the disposal was not at arm’s length (for example to a connected person);
- less cost — what the company paid, including the incidental costs of buying it (legal fees, stamp duty land tax), plus any enhancement expenditure still reflected in the asset;
- less incidental costs of disposal — agents’ commission, legal and valuation fees on the sale;
- less indexation allowance — an inflation adjustment for assets held before January 2018. Indexation was frozen at December 2017, so it only covers the period from acquisition to then. It can reduce a gain to nil, but it can never create or increase a loss (TCGA 1992 s53). Tax Optimiser works it out from the acquisition date — see Indexation allowance below.
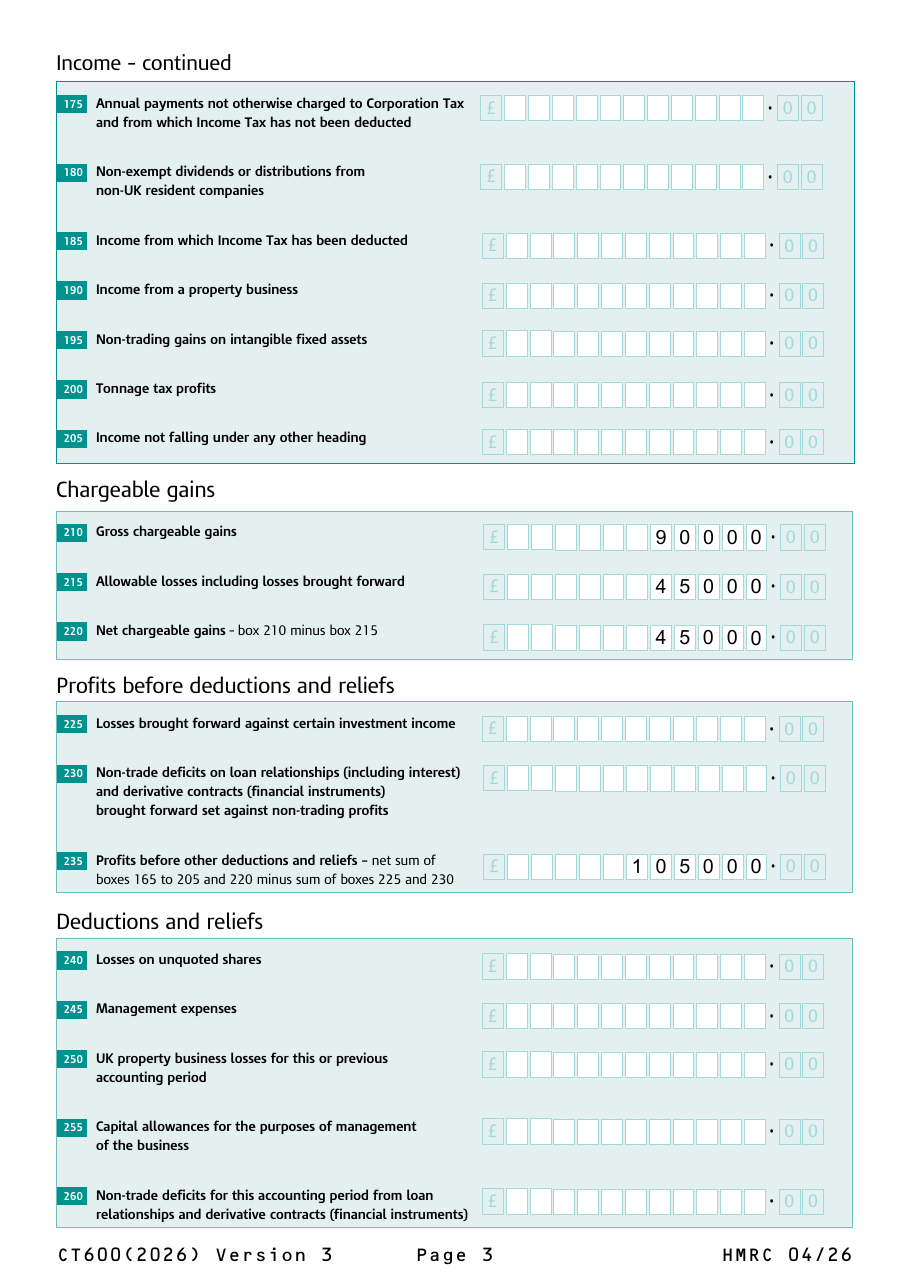
Gains for the period are added up, allowable capital losses are set against them, and the net chargeable gain joins trading profits, property income and interest in the company’s total profits (CT600 box 235). A net capital loss is not deducted from anything else: it carries forward against future gains.
Some disposals are not chargeable gains at all. Plant and machinery on which capital allowances were claimed is dealt with through the capital allowances pools; goodwill and intangible assets created or acquired from April 2002 fall under the intangible fixed assets regime; and shares in a trading company or group may qualify for the substantial shareholding exemption.
What Tax Optimiser calculates, and what it does not
The Chargeable Gains tab works out the gain or loss on each disposal from the figures you enter, including the indexation allowance from the Retail Prices Index when you give an acquisition date. It sets current losses and losses brought forward against the gains, fills in CT600 boxes 210, 215, 220 and 825, and carries any unused losses forward.
It does not calculate the reliefs and special rules that change the figures going in. Work these out separately and enter the result:
- Indexation on enhancement expenditure incurred in a different month from the purchase — tick Manual and enter the total indexation for the disposal.
- Substantial shareholding exemption — leave an exempt disposal off the tab.
- Rollover relief and no gain / no loss transfers within a group — enter the cost or proceeds as adjusted by the relief.
- Share pooling and part disposals — enter the pooled or apportioned cost, and tick Manual to enter the pool’s indexed rise yourself.
- Negligible value claims — enter the deemed disposal as its own row.
Step 1: record each disposal
Open Corp Tax Calculations and choose Chargeable Gains from the Sections menu. Click Add Disposal for each asset sold in the period and fill in the row: the asset, the disposal date (normally the date the contract became unconditional), the Proceeds, the date the asset was Acquired, its Cost and the Costs of selling it. The Indexation and Gain / (loss) columns are calculated as you type, in whole pounds.
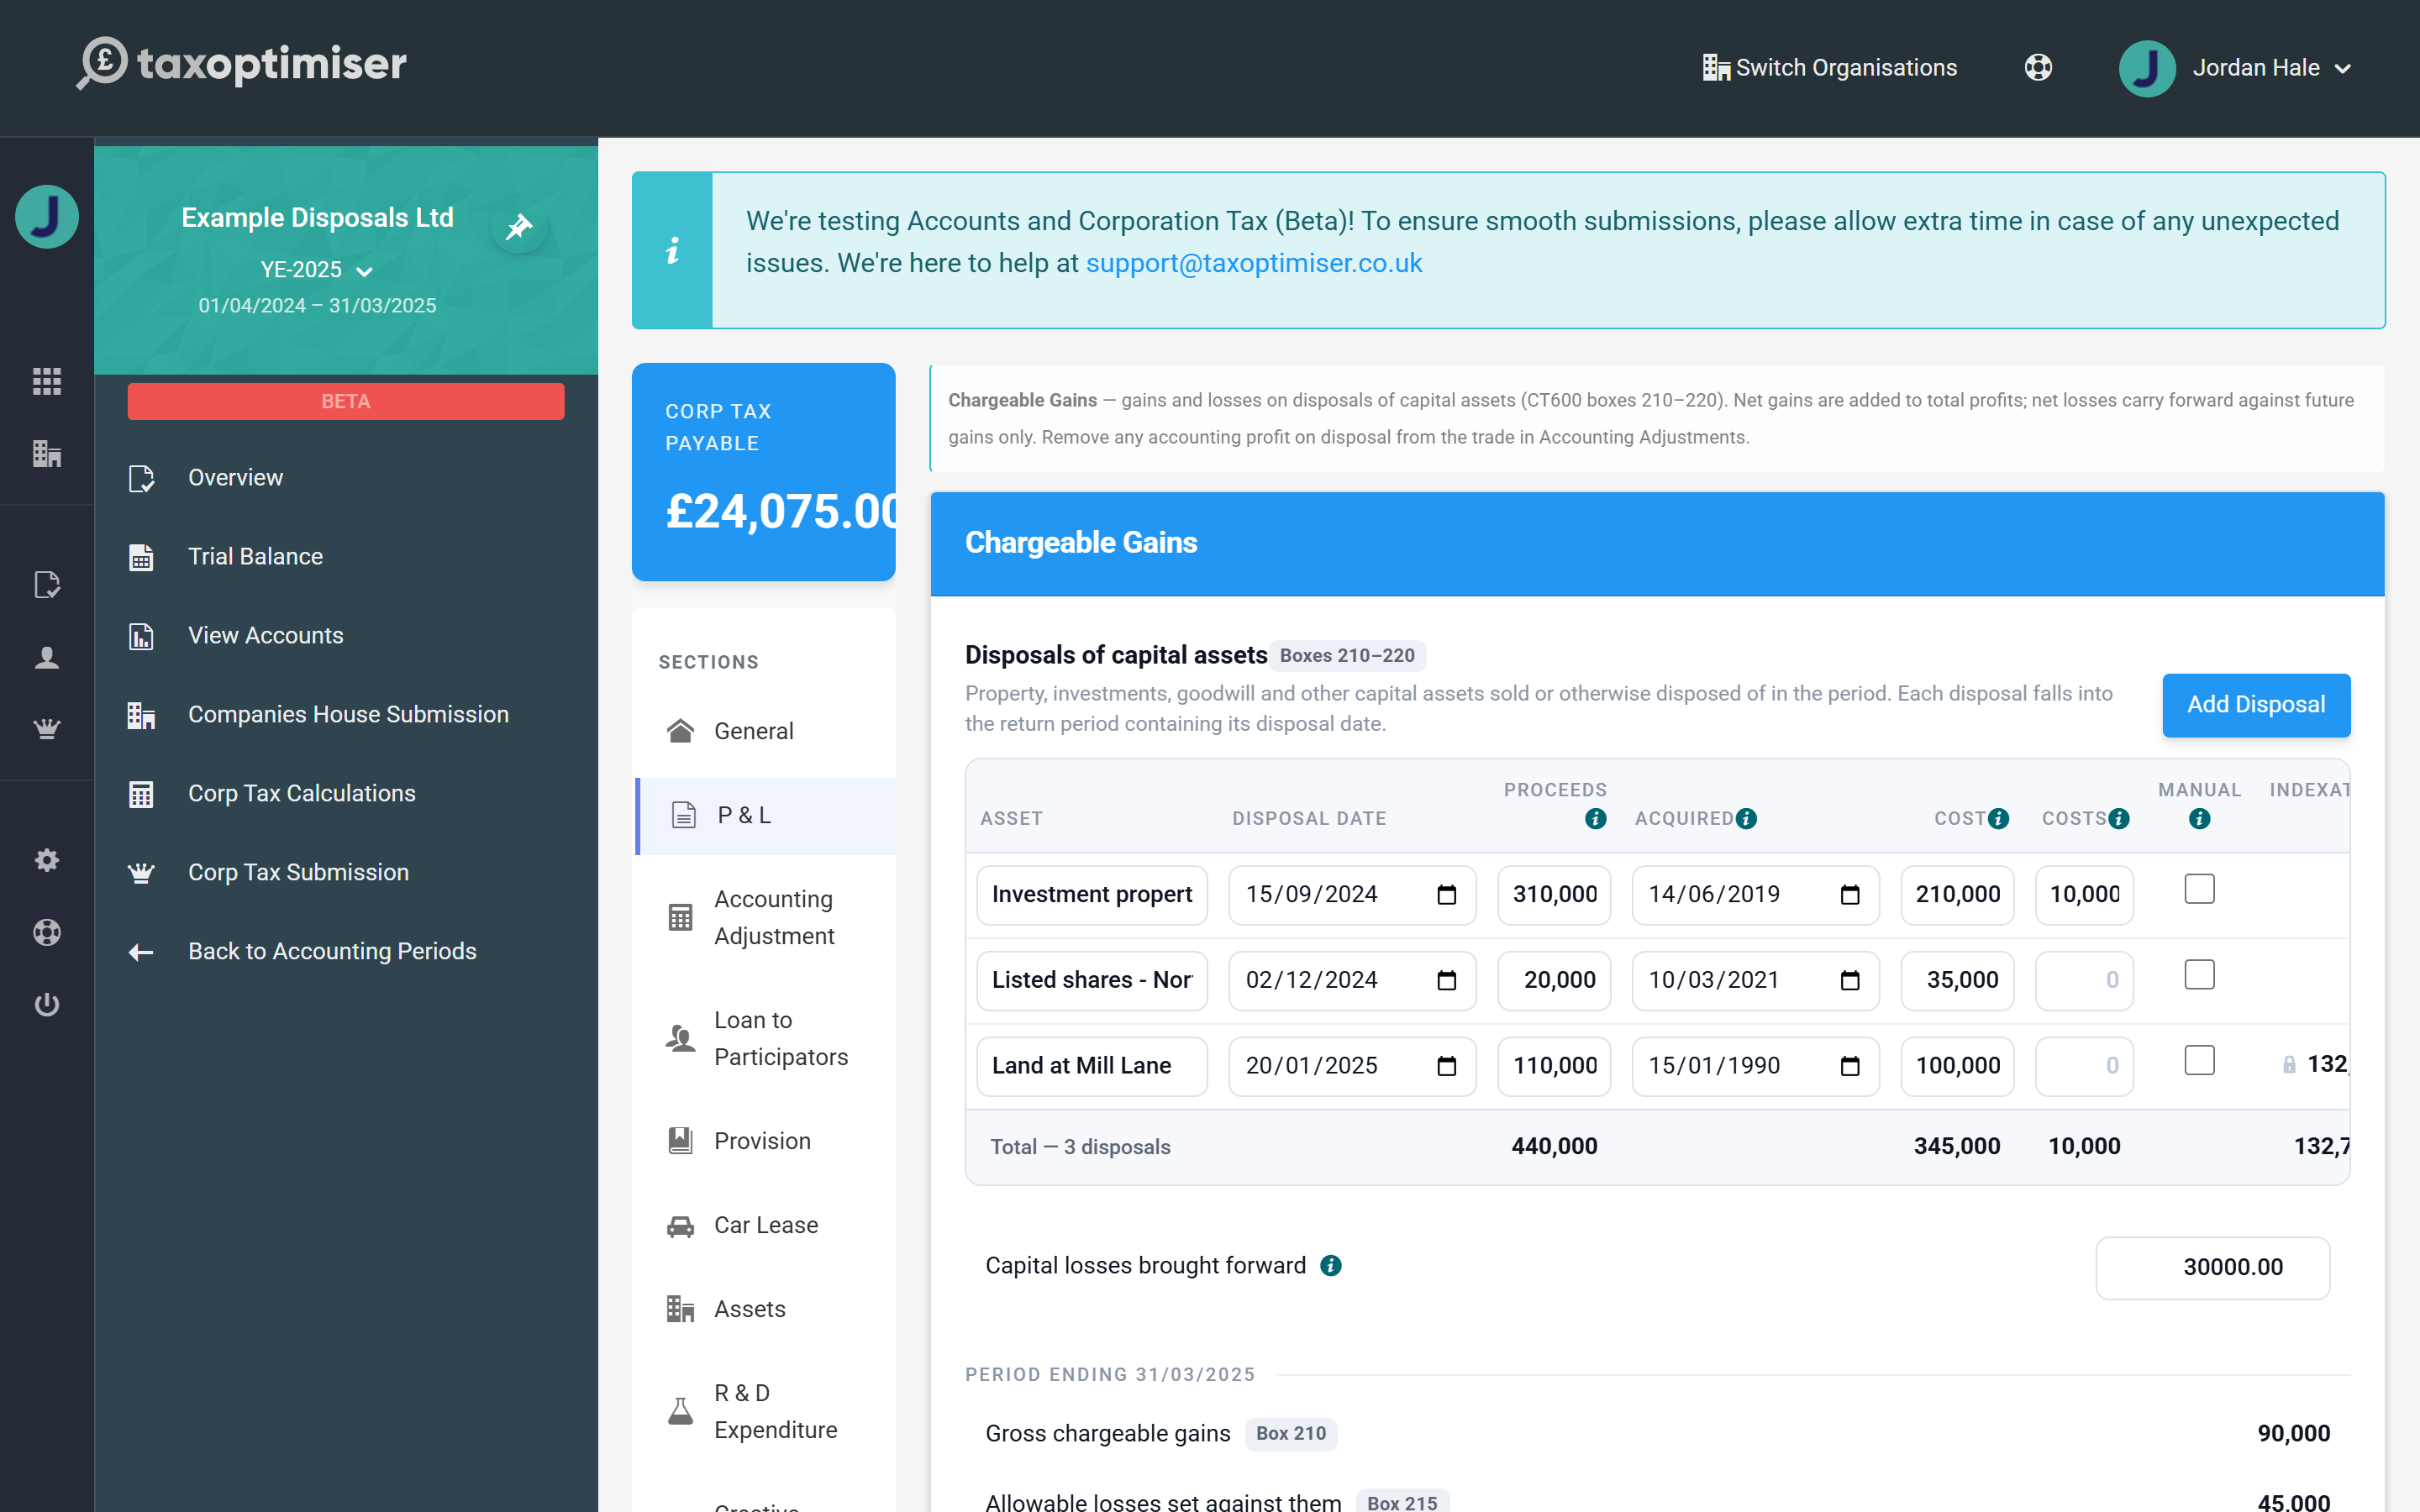
In the example, Example Disposals Ltd sold three assets:
- an investment property bought in 2019 for £210,000, sold for £310,000 with £10,000 of agents’ and legal fees — a £90,000 gain;
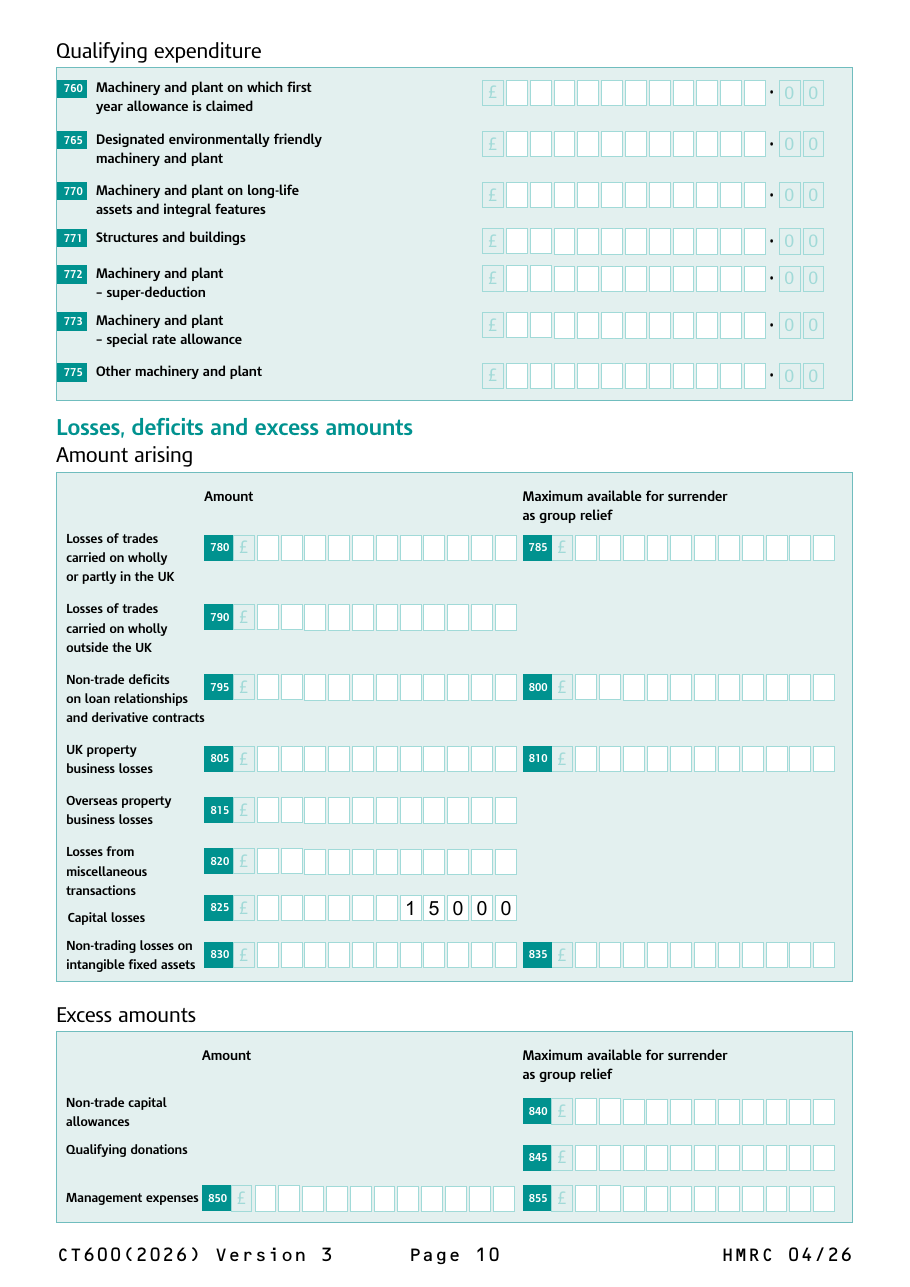
- listed shares bought in 2021 for £35,000, sold for £20,000 — a £15,000 loss;
- land at Mill Lane bought in January 1990 for £100,000 and sold for £110,000. Indexation of £132,700 wipes out the £10,000 gain — but only down to nil, so the land shows neither a gain nor a loss.
The first two were bought after December 2017, so their indexation is nil.
Indexation allowance
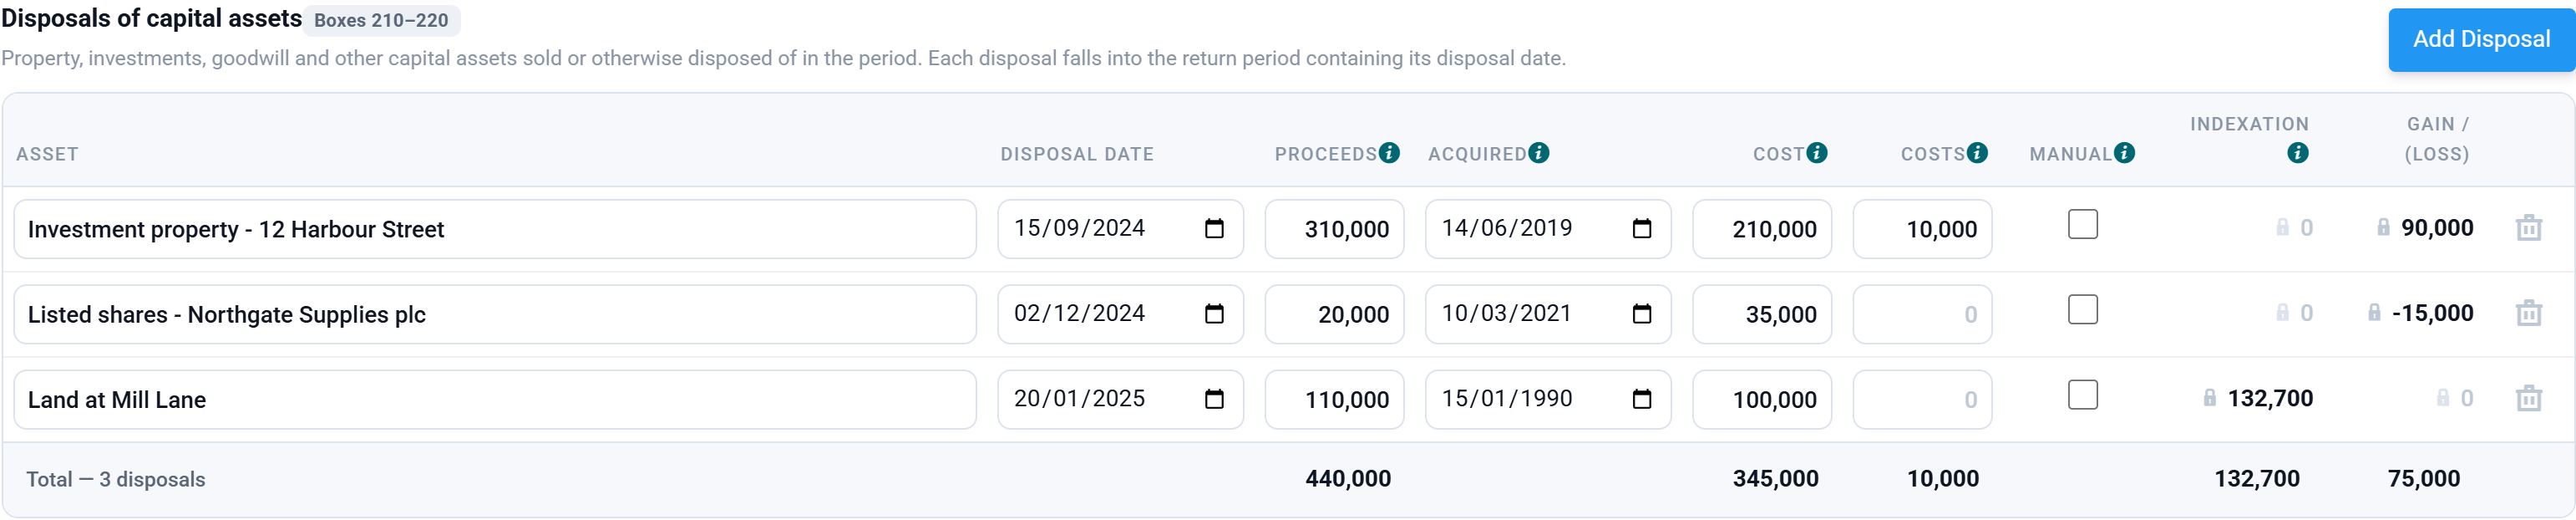
When a row has an Acquired date, Tax Optimiser works out the indexation allowance for you and locks the cell:
- the indexation factor is the rise in the Retail Prices Index from the month of acquisition to the month of disposal — or to December 2017 if the disposal is later — divided by the index at acquisition, rounded to three decimal places;
- the factor is applied to the Cost column. The Costs column is the cost of selling, which is never indexed;
- anything bought after December 2017 gets no indexation;
- for an asset held on 31 March 1982, enter its market value on that date as the cost: indexation then runs from March 1982, and the Considerations list reminds you to check.
For Mill Lane the RPI rose from 119.5 in January 1990 to 278.1 in December 2017, a factor of 1.327. On a £100,000 cost that is £132,700.
Tick Manual to type the figure in yourself — for example when enhancement expenditure was incurred in a later month and needs its own factor, or for shares from a pool. Rows without an acquisition date also keep a typed figure.
Step 2: enter capital losses brought forward
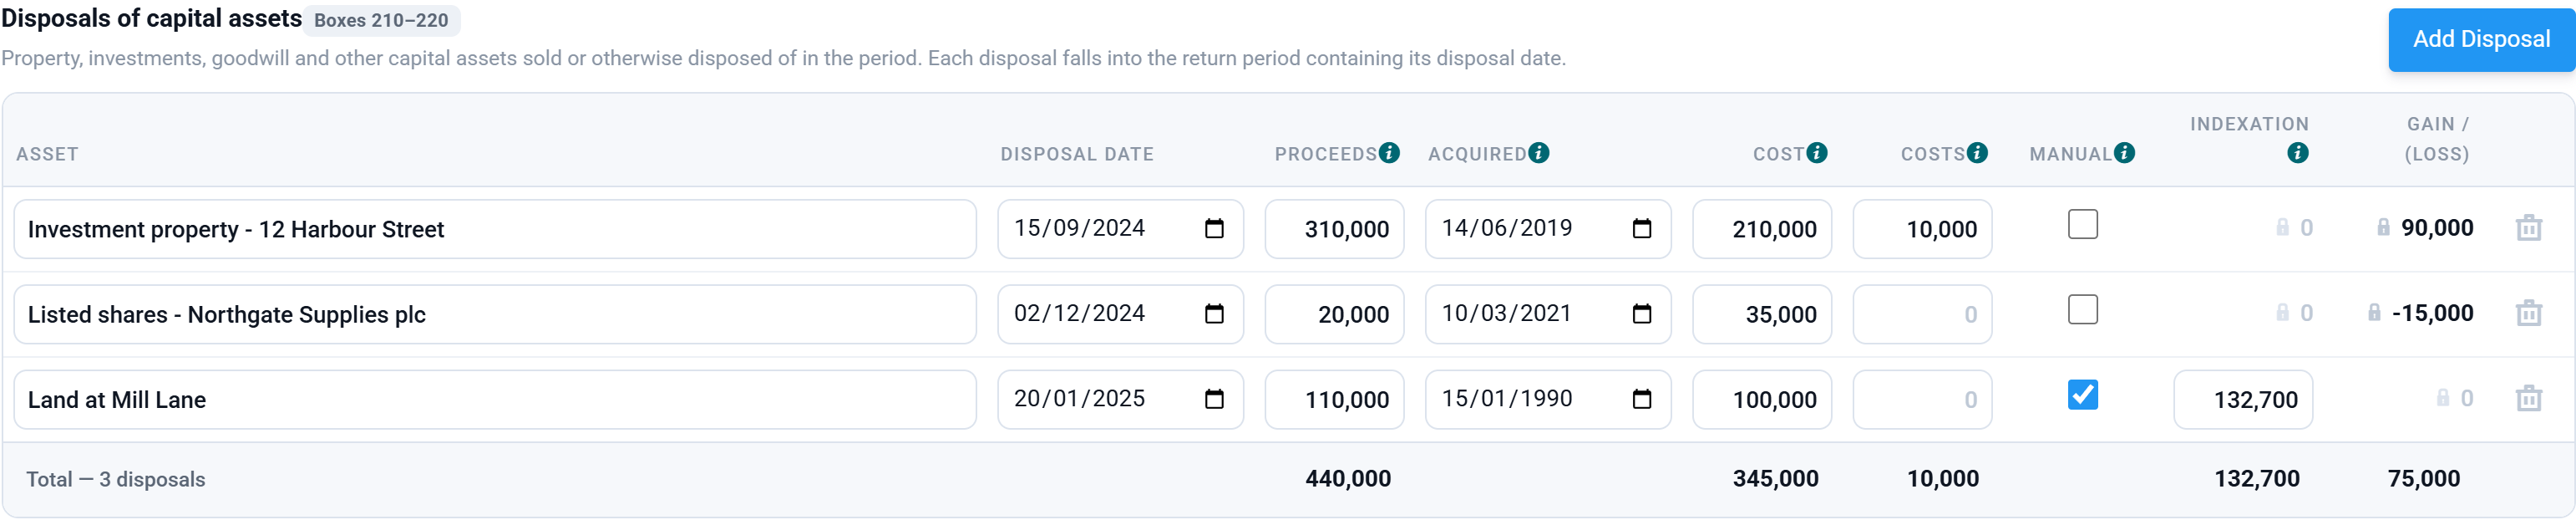
Below the table, enter any Capital losses brought forward from earlier periods — the carried-forward figure from last year’s computation. The summary then shows, for each return period, what goes in each box and what is left to carry forward.
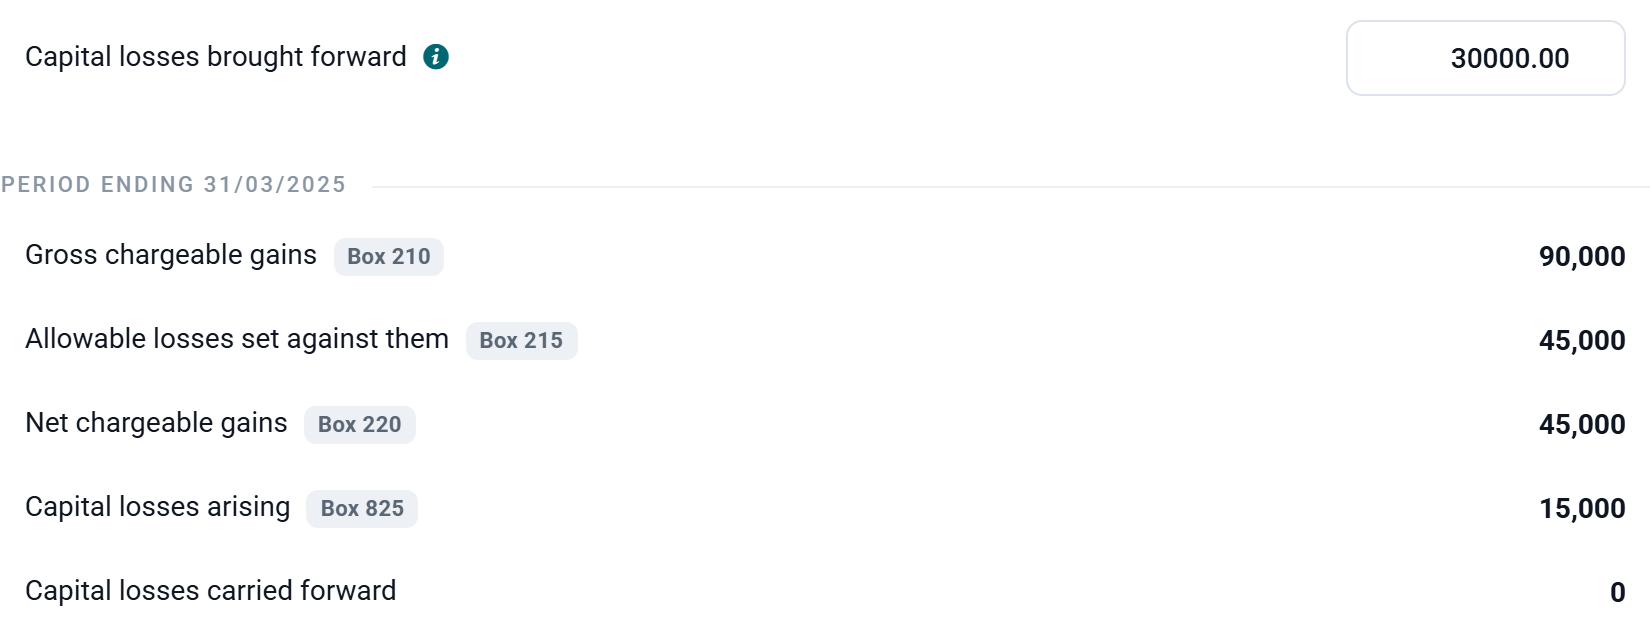
Here the £90,000 gain is reduced first by the £15,000 loss of the same period and then by £30,000 of losses brought forward, leaving a net chargeable gain of £45,000 and nothing to carry forward. Losses brought forward are only used up to the amount of the gains; any excess stays in the pool.
Step 3: take the accounts profit out of the trade
The profit or loss on disposal in the accounts is not the chargeable gain: it is measured against the asset’s carrying value, not its tax cost, and ignores indexation. It must be taken out of the trading profit so the disposal is not taxed twice.
- For assets in the capital allowances pools, Tax Optimiser already does this: the accounts profit or loss on disposal is reversed automatically in the accounts adjustments.
- For anything else — investment property, shares, land — open Accounting Adjustment. On the Income tab, add a row for an accounts profit, entering it as both the Non-Taxable and the P/L Amount. For an accounts loss, disallow it against its P&L line in the P & L section.
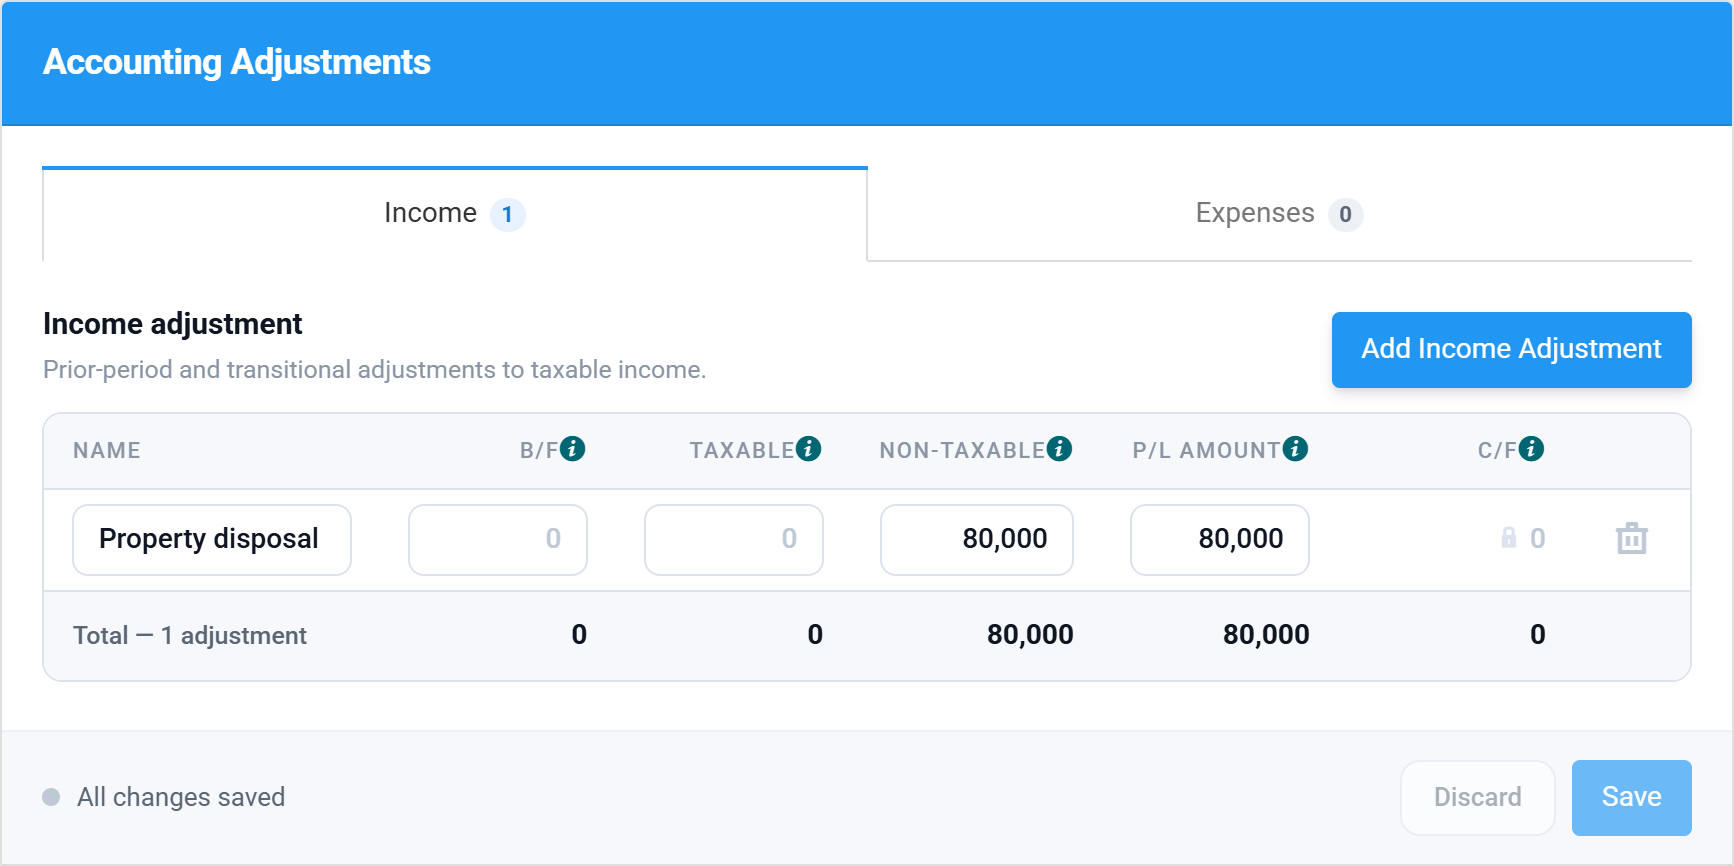
In the example the accounts show an £80,000 profit on the property (the proceeds less its carrying value). The income adjustment takes it out, so the trading profit is £60,000 and the £45,000 net chargeable gain is added separately. The shares had already been written down in the accounts in an earlier year, so there is no accounts loss to reverse — but the capital loss for tax, measured against cost, is still £15,000. The Mill Lane land was carried at its £110,000 fair value, so its sale made no accounts profit either.
Where the gain shows up
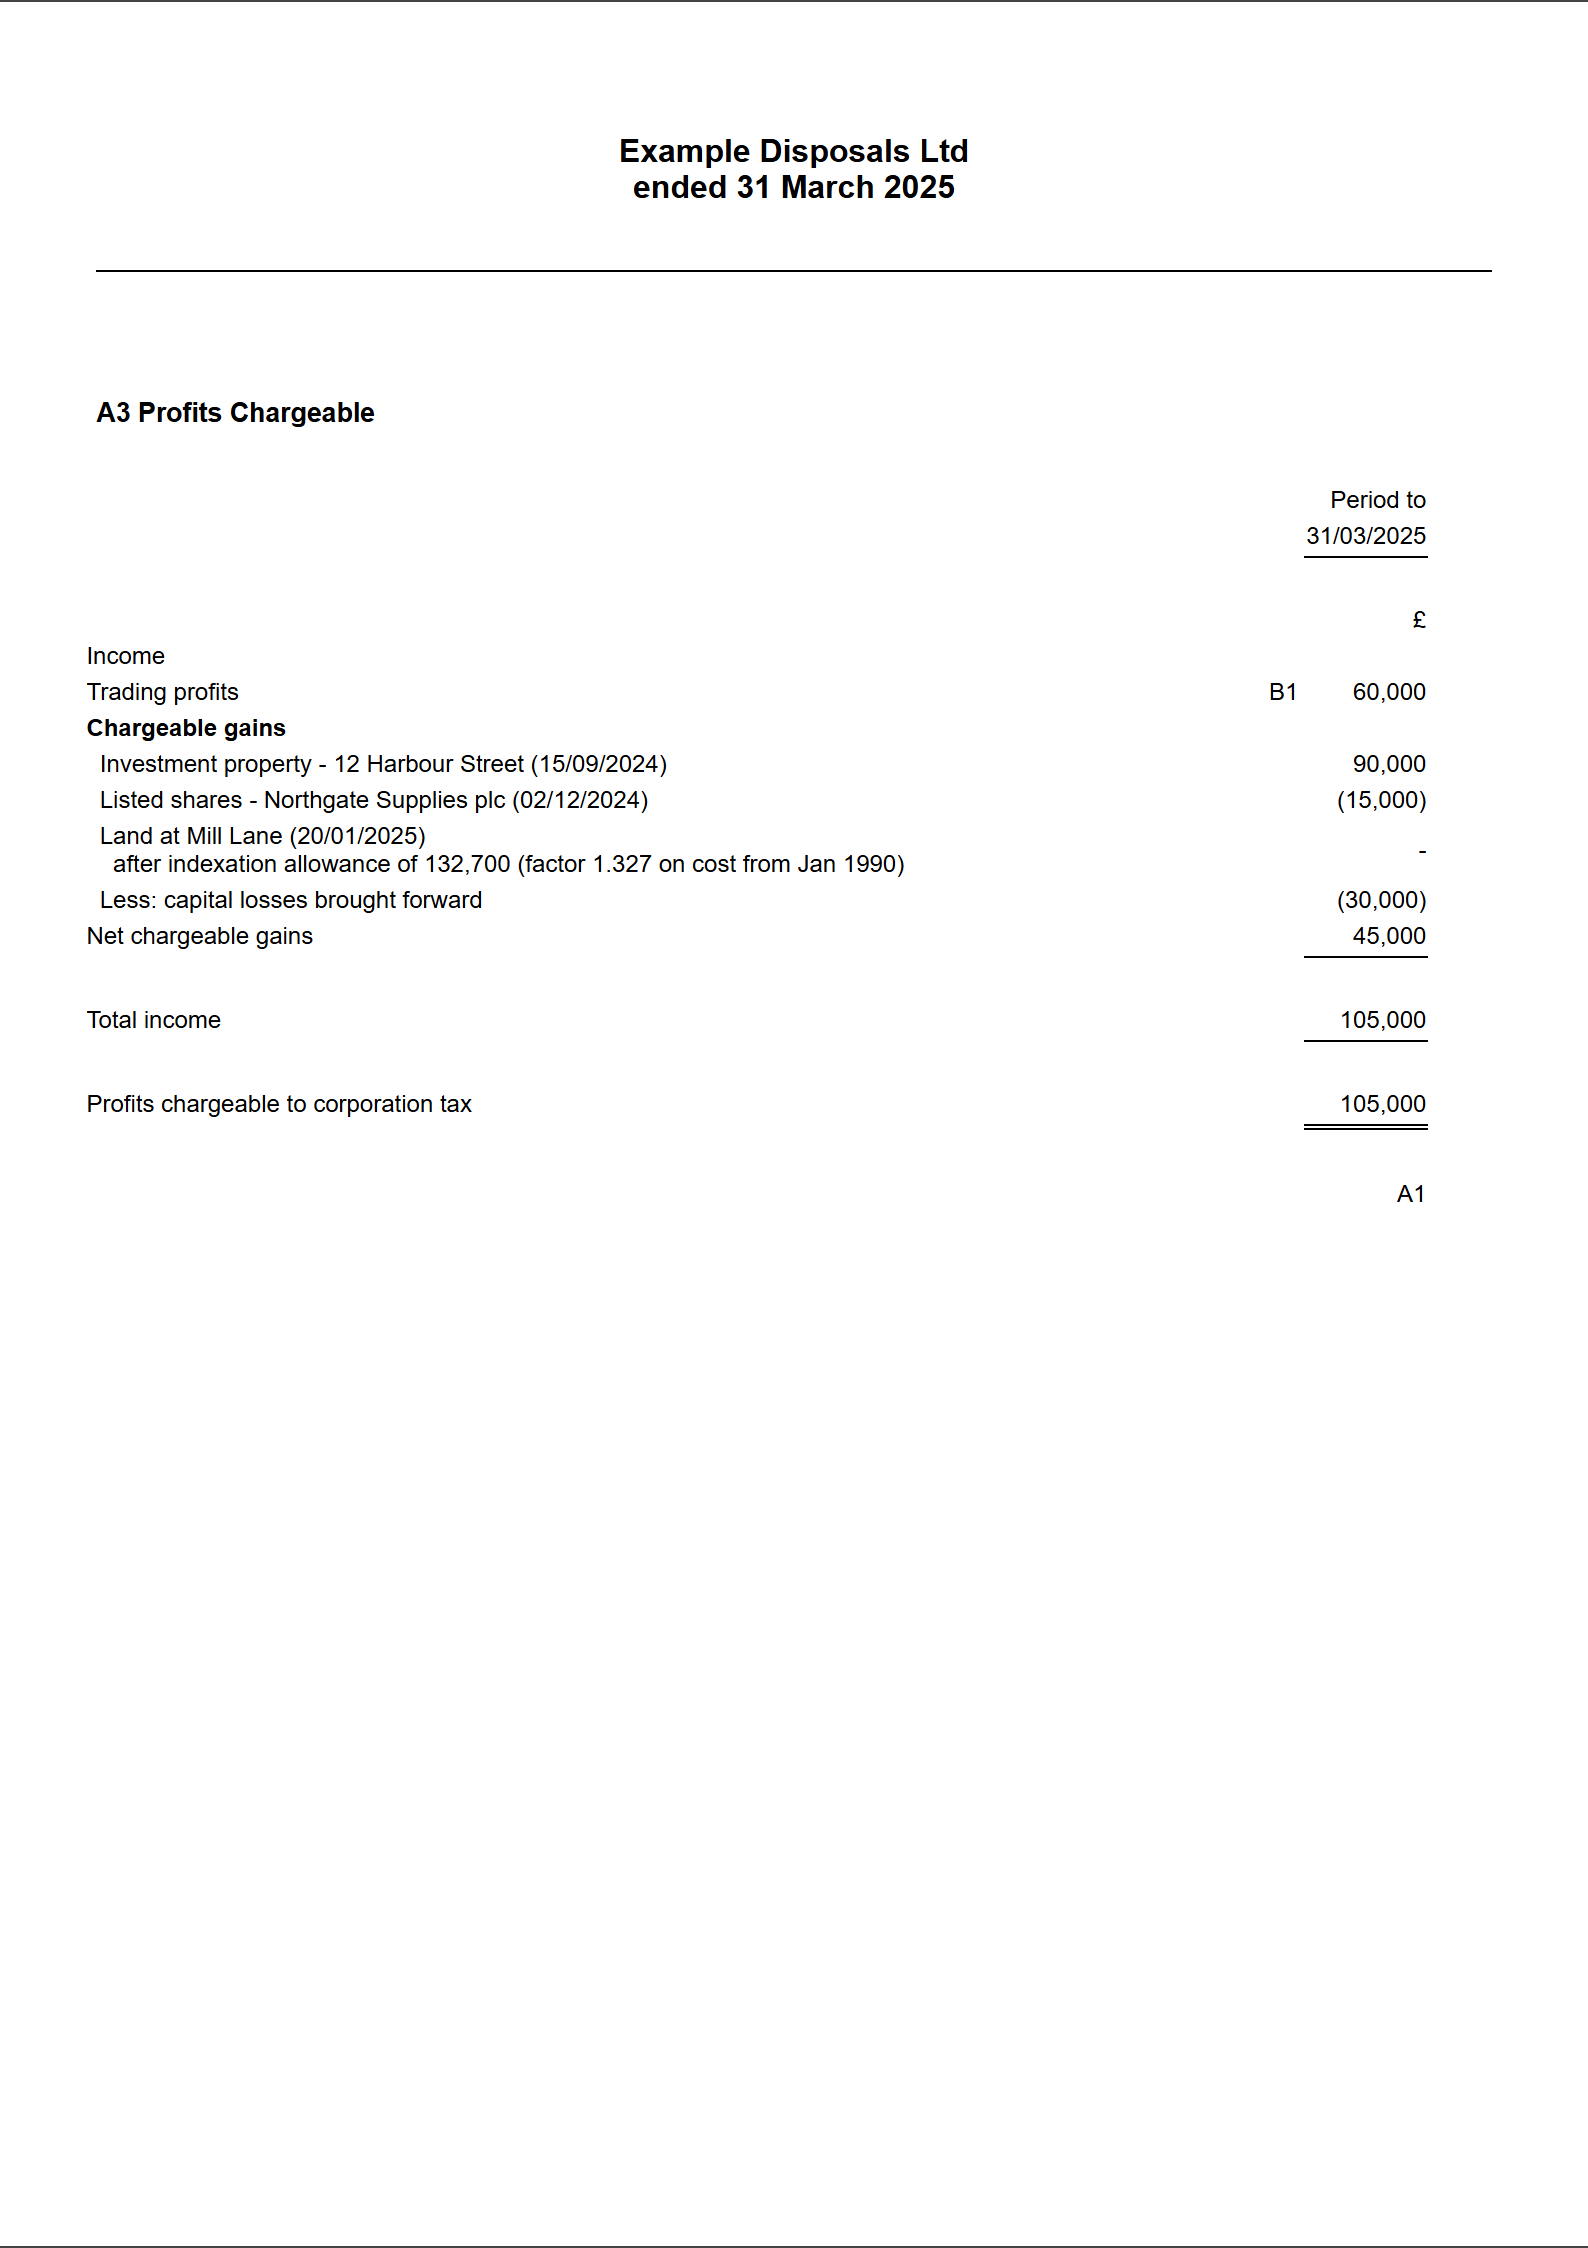
The Corp Tax Payable headline updates straight away — £24,075 in the example: total profits of £105,000 taxed at 25% less marginal relief. The computation document lists each disposal and the losses used under Chargeable gains on the profits chargeable page, with the indexation allowance and factor under any indexed disposal.
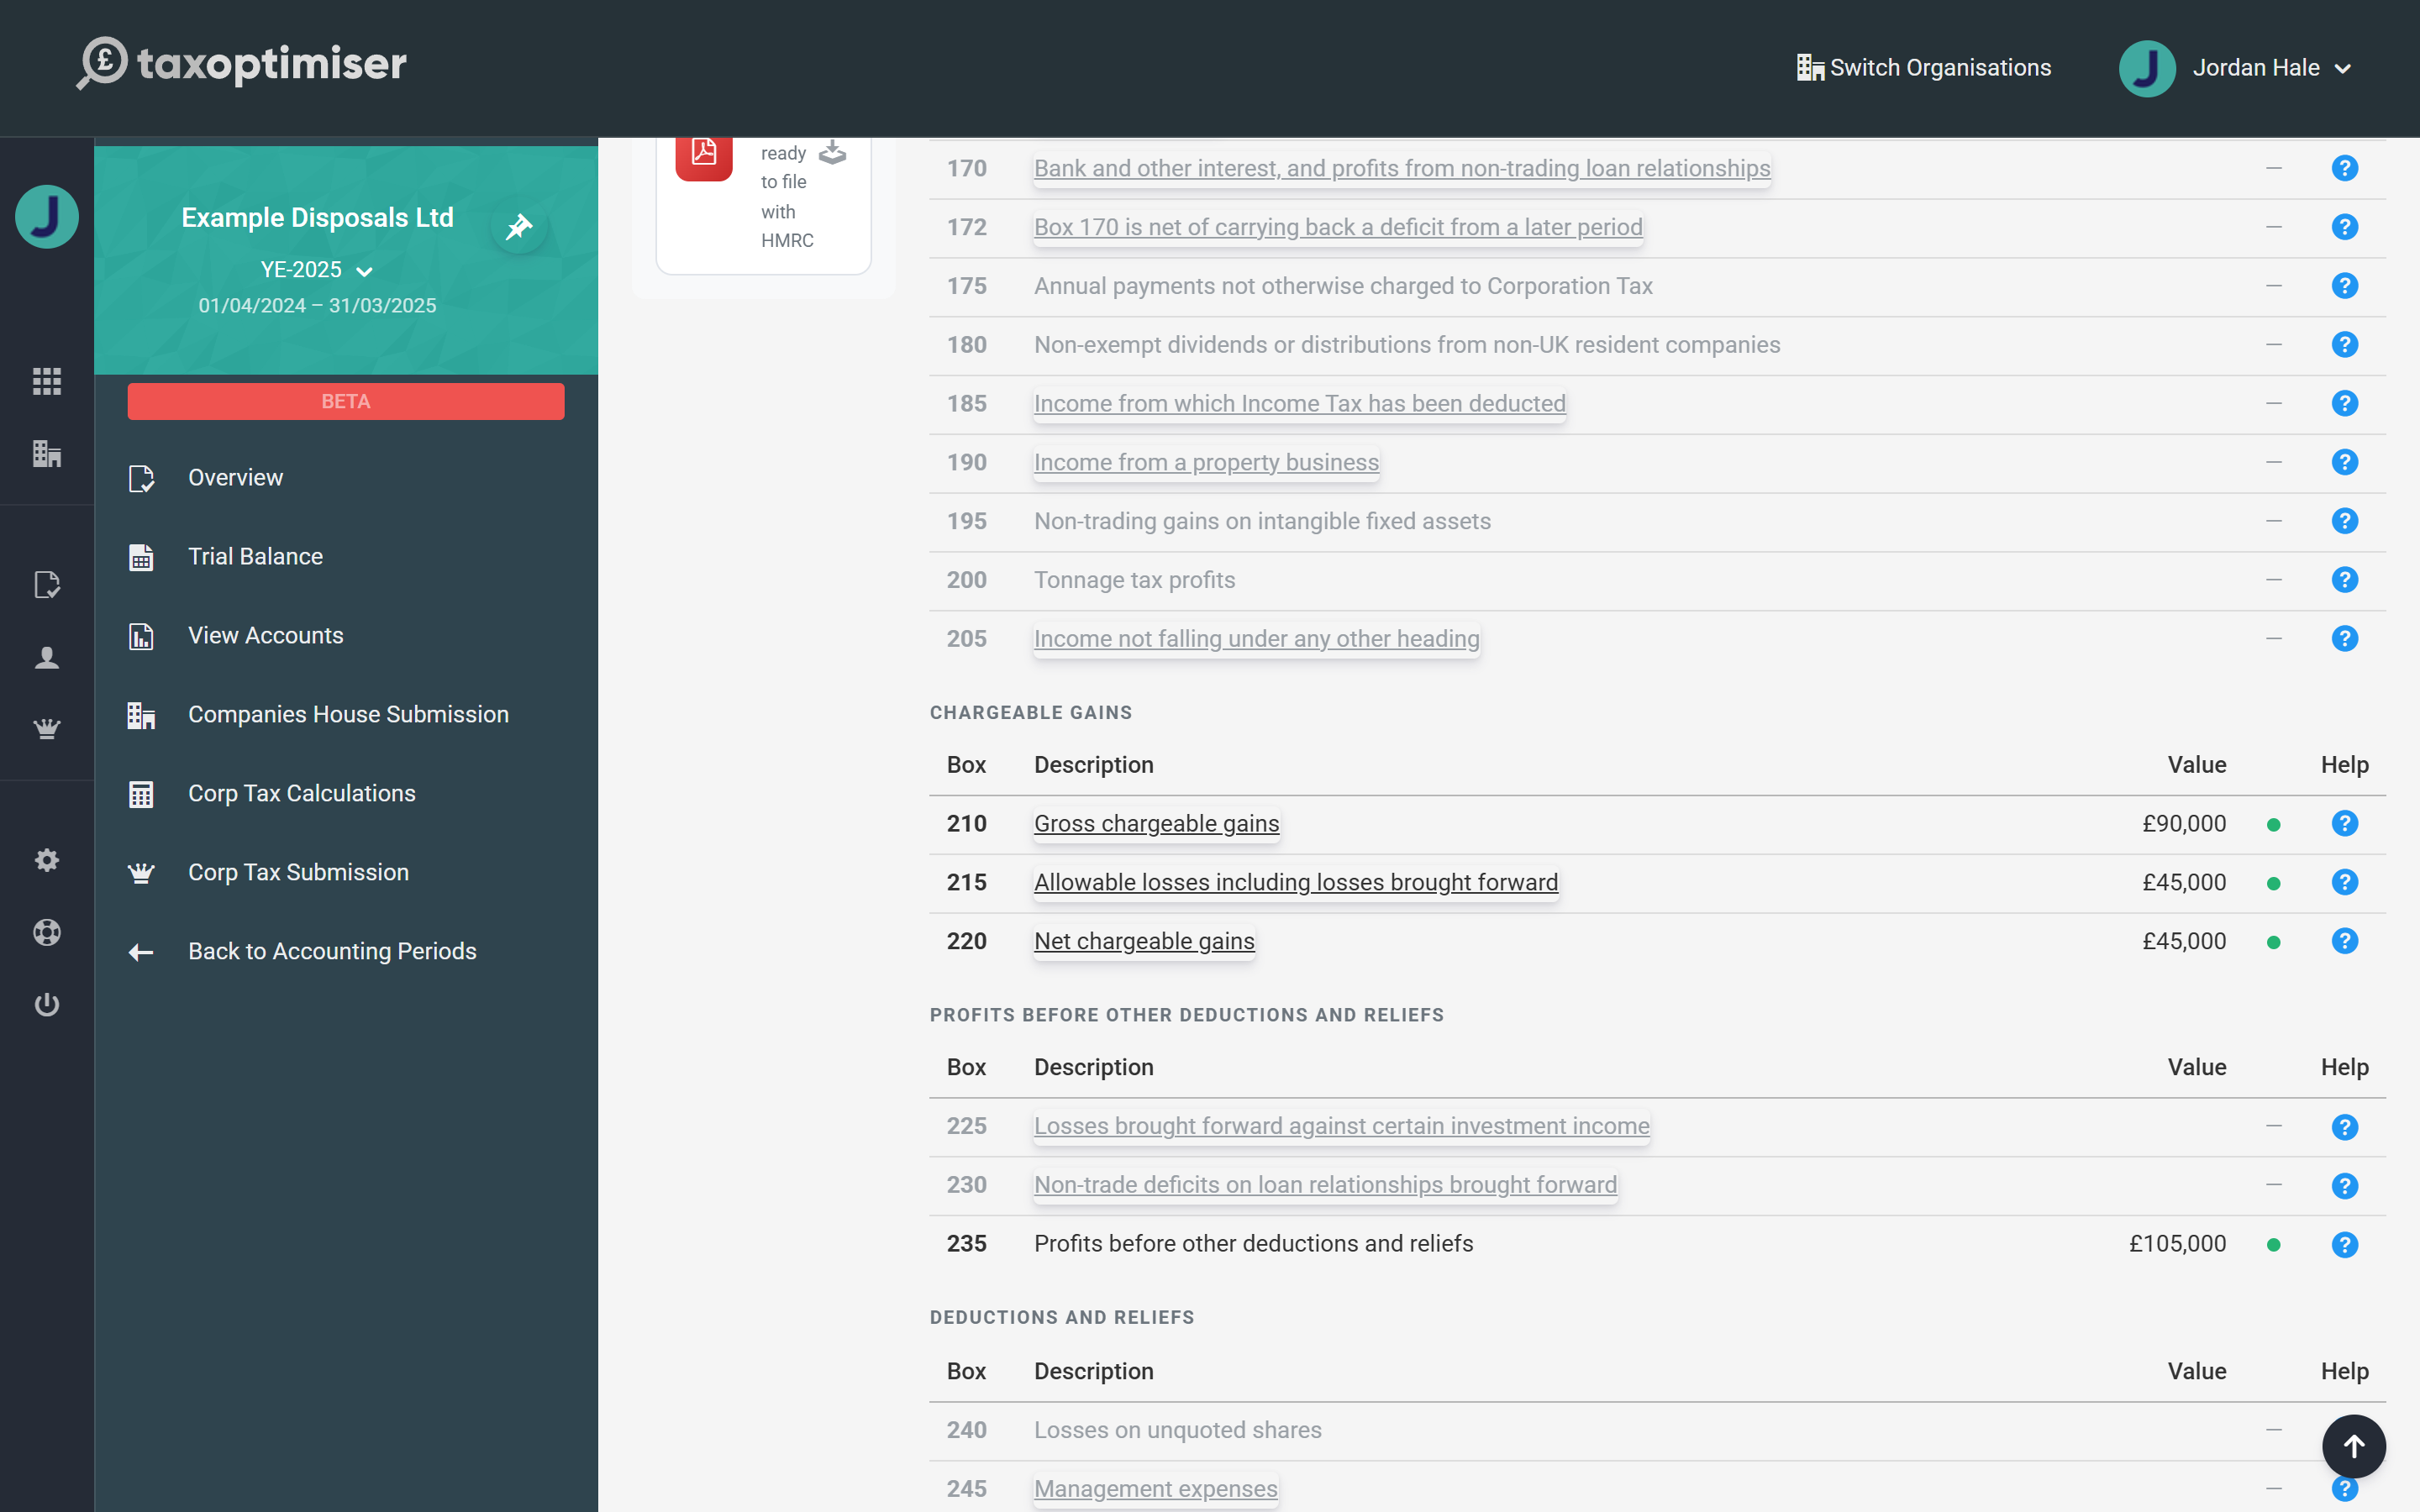
The CT600 Boxes section shows the return boxes, and the CT600 itself carries them on page 3, with the capital loss arising on page 10.
Capital losses
- Losses of the period come off gains of the period first, then losses brought forward are used. Both are included in box 215.
- Capital losses only relieve gains. They are never set against trading profits or other income, and they cannot be carried back.
- Unused losses carry forward indefinitely. The Chargeable Gains tab shows the carried-forward figure, and the computation’s carried-forward amounts page lists it for next year.
- Box 825 reports the whole capital loss arising in the period, even where some of it was used against the period’s gains.
Long periods of account and charities
When the accounts run for more than twelve months, the return is split into two periods. Each disposal falls into the return period that contains its disposal date, losses brought forward are used in the first period first, and anything unused passes to the second. A disposal dated outside the accounting period is flagged as an error rather than dropped.
A charity or CASC claiming full exemption applies its gains for charitable purposes, so none are charged: the disposals can still be recorded, but boxes 210 to 220 stay at nil.
CT600 boxes
Box 210 — Gross chargeable gains
The total of the gains on disposals in the return period, before any losses. Disposals that made a loss are not netted off here.
Box 215 — Allowable losses including losses brought forward
The capital losses actually set against the gains in box 210: this period’s losses first, then losses brought forward. It never exceeds box 210.
Box 220 — Net chargeable gains
Box 210 minus box 215. It is added to the other income boxes to give box 235. When losses wipe out the gains, boxes 210 and 215 are still reported and box 220 is nil.
Box 825 — Capital losses
The capital losses arising in the period, in the losses summary on page 10 — reported in full whether or not they were set against gains in box 215.
Frequently asked questions
Do companies pay Capital Gains Tax?
No. A company’s chargeable gains are added to its other profits and taxed as Corporation Tax, at the same rate as the rest of its profits. They go on the CT600 in boxes 210 to 220.
Can a capital loss reduce my trading profit?
No. Capital losses can only be set against chargeable gains, in the same period or a later one. They are carried forward indefinitely until there are gains to use them against.
Does Tax Optimiser calculate indexation allowance?
Yes. Enter the date the asset was acquired and the allowance is worked out from the Retail Prices Index, frozen at December 2017, and applied to the cost. Assets bought from January 2018 get none, and it can reduce a gain to nil but never create or increase a loss. Tick Manual to enter your own figure, for example for enhancement expenditure or pooled shares.
Why is the gain on the CT600 different from the profit in my accounts?
The accounts measure the profit against the asset’s carrying value, which may include revaluations or write-downs; the chargeable gain is measured against its tax cost, less incidental costs and indexation. Take the accounts figure out of the trade in Accounting Adjustment and record the gain on the Chargeable Gains tab.
What about equipment and vehicles I sold?
Plant and machinery on which capital allowances were claimed is dealt with in the capital allowances pools, not as a chargeable gain. Record the disposal proceeds on the Assets section instead.
Where do I enter losses brought forward from last year?
In Capital losses brought forward on the Chargeable Gains tab. Use the carried-forward figure from last year’s computation.
My accounts run for 15 months. Which return does a disposal go on?
The return period containing the disposal date. Tax Optimiser splits the disposals automatically and passes any unused losses from the first period to the second.
Where to go next
- Building the Corporation Tax computation — the other sections of Corp Tax Calculations.
- CT600 box-by-box guide — every box on the main return.
- HMRC’s Capital Gains Manual — the detailed rules, including indexation, rollover relief and the substantial shareholding exemption.