A company that lets out property has a UK property business alongside (or instead of) its trade. Corporation Tax treats the two separately: rents less the costs of letting are taxed as a property business (CT600 box 190), not as trading profit, and a property loss has its own relief (boxes 805 and 250). Tax Optimiser handles all of this once you tell it which profit-and-loss lines belong to the property business.
When a company has a property business
If the trial balance contains rental income — from a buy-to-let, a commercial unit, or space sub-let in the company's own premises — that income and the costs of earning it (agent fees, repairs, insurance, ground rent, mortgage interest on the let property) form a property business. The rule of thumb: anything that would stop if the letting stopped belongs to the property business; everything else is the trade.
Two things do not make a property business: rent the company pays for its own premises (a trade expense), and one-off profits on selling a property (a chargeable gain).
Mark the P & L lines as UK property
Open Corp Tax Calculations and go to the P & L section. Every turnover, cost-of-sales and expense line has a Type dropdown — Trade or UK property. Set the rental income line and each property cost line to UK property. The change saves straight away and the lines regroup under Property income and Property expenses, with the net result shown beneath them.
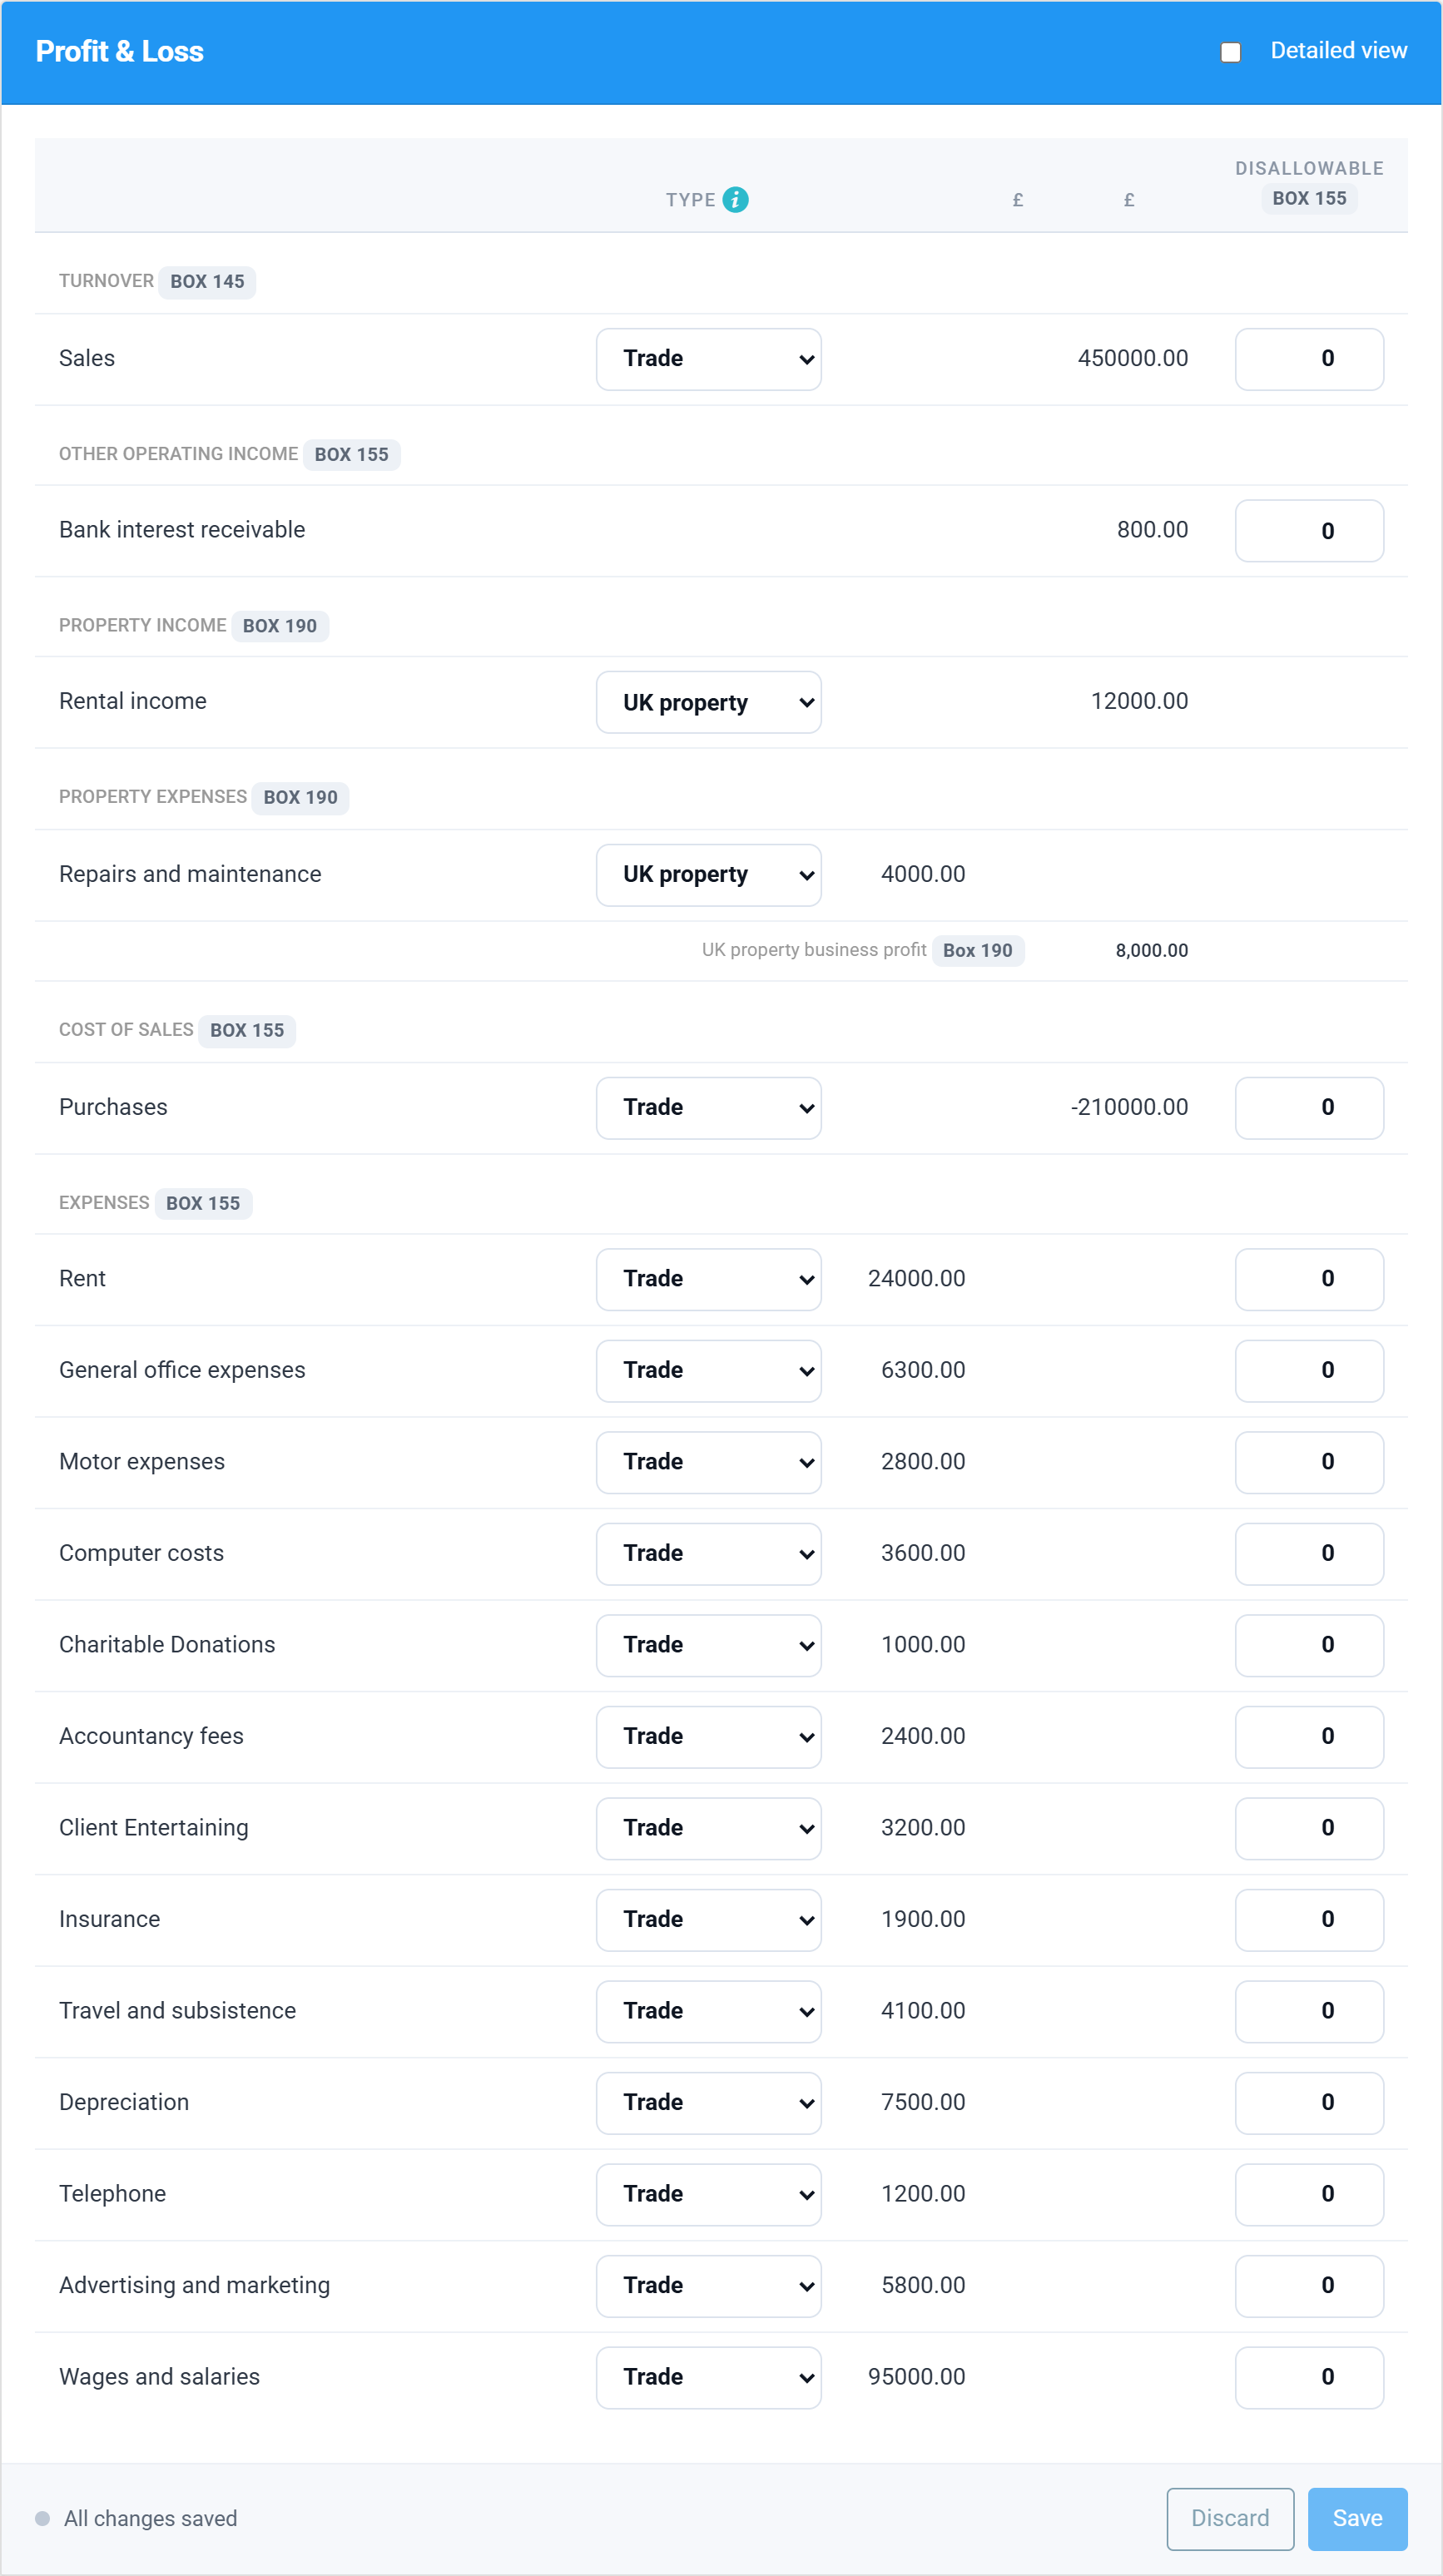
The Rental income account in the standard chart of accounts is already typed as UK property, so if you posted rents there you only need to mark the cost lines. Any account can be retyped at any time; the typing is remembered for the period.
Property expense lines have a Disallowable box just like trade lines. Enter the non-deductible part of a cost there — depreciation is the usual example — and it is added back in computing the property business result, not the trading profit.
Capital allowances of a property business
Plant and machinery used in the letting business — tools and equipment for maintaining the properties, a van used to get to them, furniture in commercial lets — qualifies for capital allowances in the property business, not the trade. The allowances are an expense of the property business and any balancing charge is a receipt of it, so they reduce box 190 (or increase the loss in box 805) and are reported on the CT600 in the boxes for allowances not included in trading profits: the annual investment allowance in box 735, writing-down allowances in box 750, balancing charges in box 755, and full expensing, structures and buildings, super-deduction and the 50% first-year allowance in boxes 733, 736, 741 and 743.
Which business claims the allowances is set at the top of the Assets section under Capital allowances claimed by. Left on Automatic, a company whose P & L lines are all typed UK property claims them in the property business; a company that also trades keeps them in the trade. Choose UK property business or Trade to override that for the period — the choice covers all of the period's pools, so a company whose assets are split between a trade and a property business needs to claim them in whichever business uses the bulk of them.
Worked example: rents £30,000, property costs £8,000 and £12,000 of maintenance tools and a van covered by the annual investment allowance — box 190 shows £10,000, box 735 shows £12,000, and box 155 and box 690 stay at nil.
What happens in the computation
Marking the lines moves them out of the trade: on the Accounts Adjustments schedule the property receipts are deducted and the property costs added back, so the trading profit (and box 145 turnover, box 155 trading profit) contains only the trade. The property business gets its own schedule showing receipts, expenses and the net result.
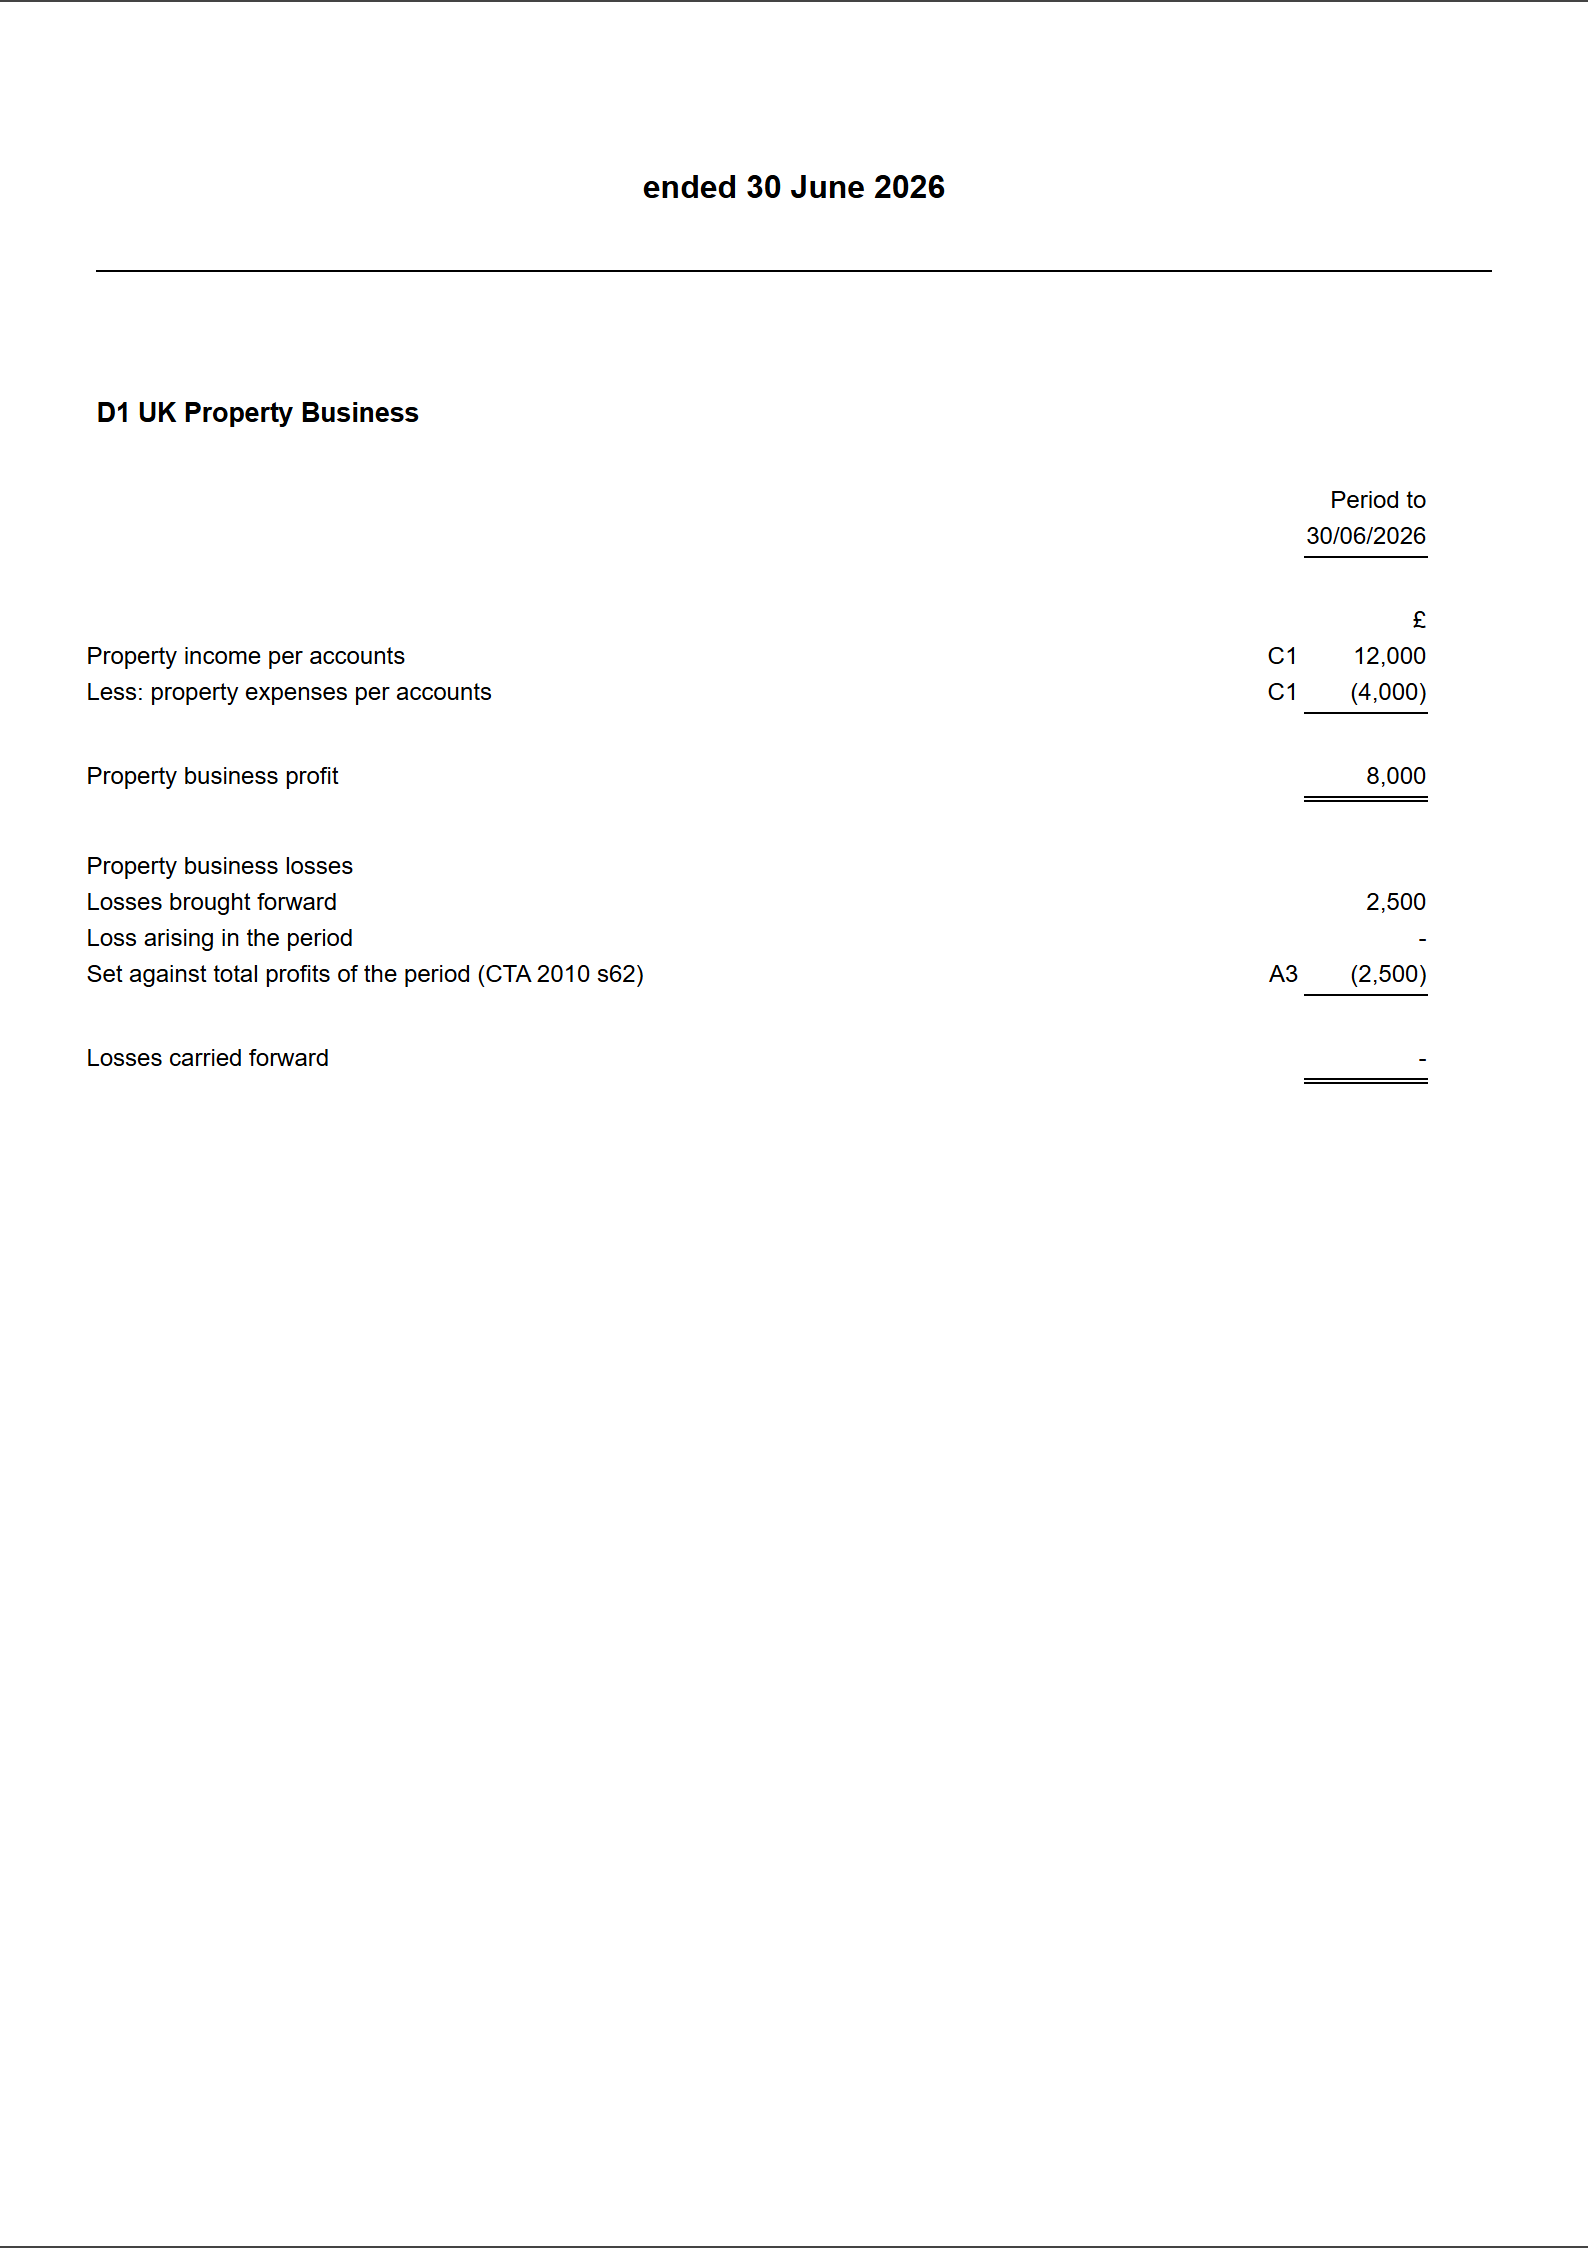
A net profit goes to box 190 and is added to the trade profit in profits chargeable. It is the net figure, not the gross rents — HMRC's box 190 is the profit of the property business after its own expenses.
Property losses: boxes 805 and 250
If the property costs exceed the rents, the property business has made a loss. It is reported as the loss arising in box 805 and, because a company's property loss is set against its total profits of the same period automatically, the amount used appears in box 250. Anything that cannot be used (because there were not enough profits) carries forward and is set against the next period's total profits in the same way.
Losses brought forward from earlier periods are entered in the Losses section under UK property business losses: put the unrelieved balance in UK Property Loss B/F. The section shows the property result for the period, the loss arising, the amount set against total profits (box 250) and the balance carried forward.
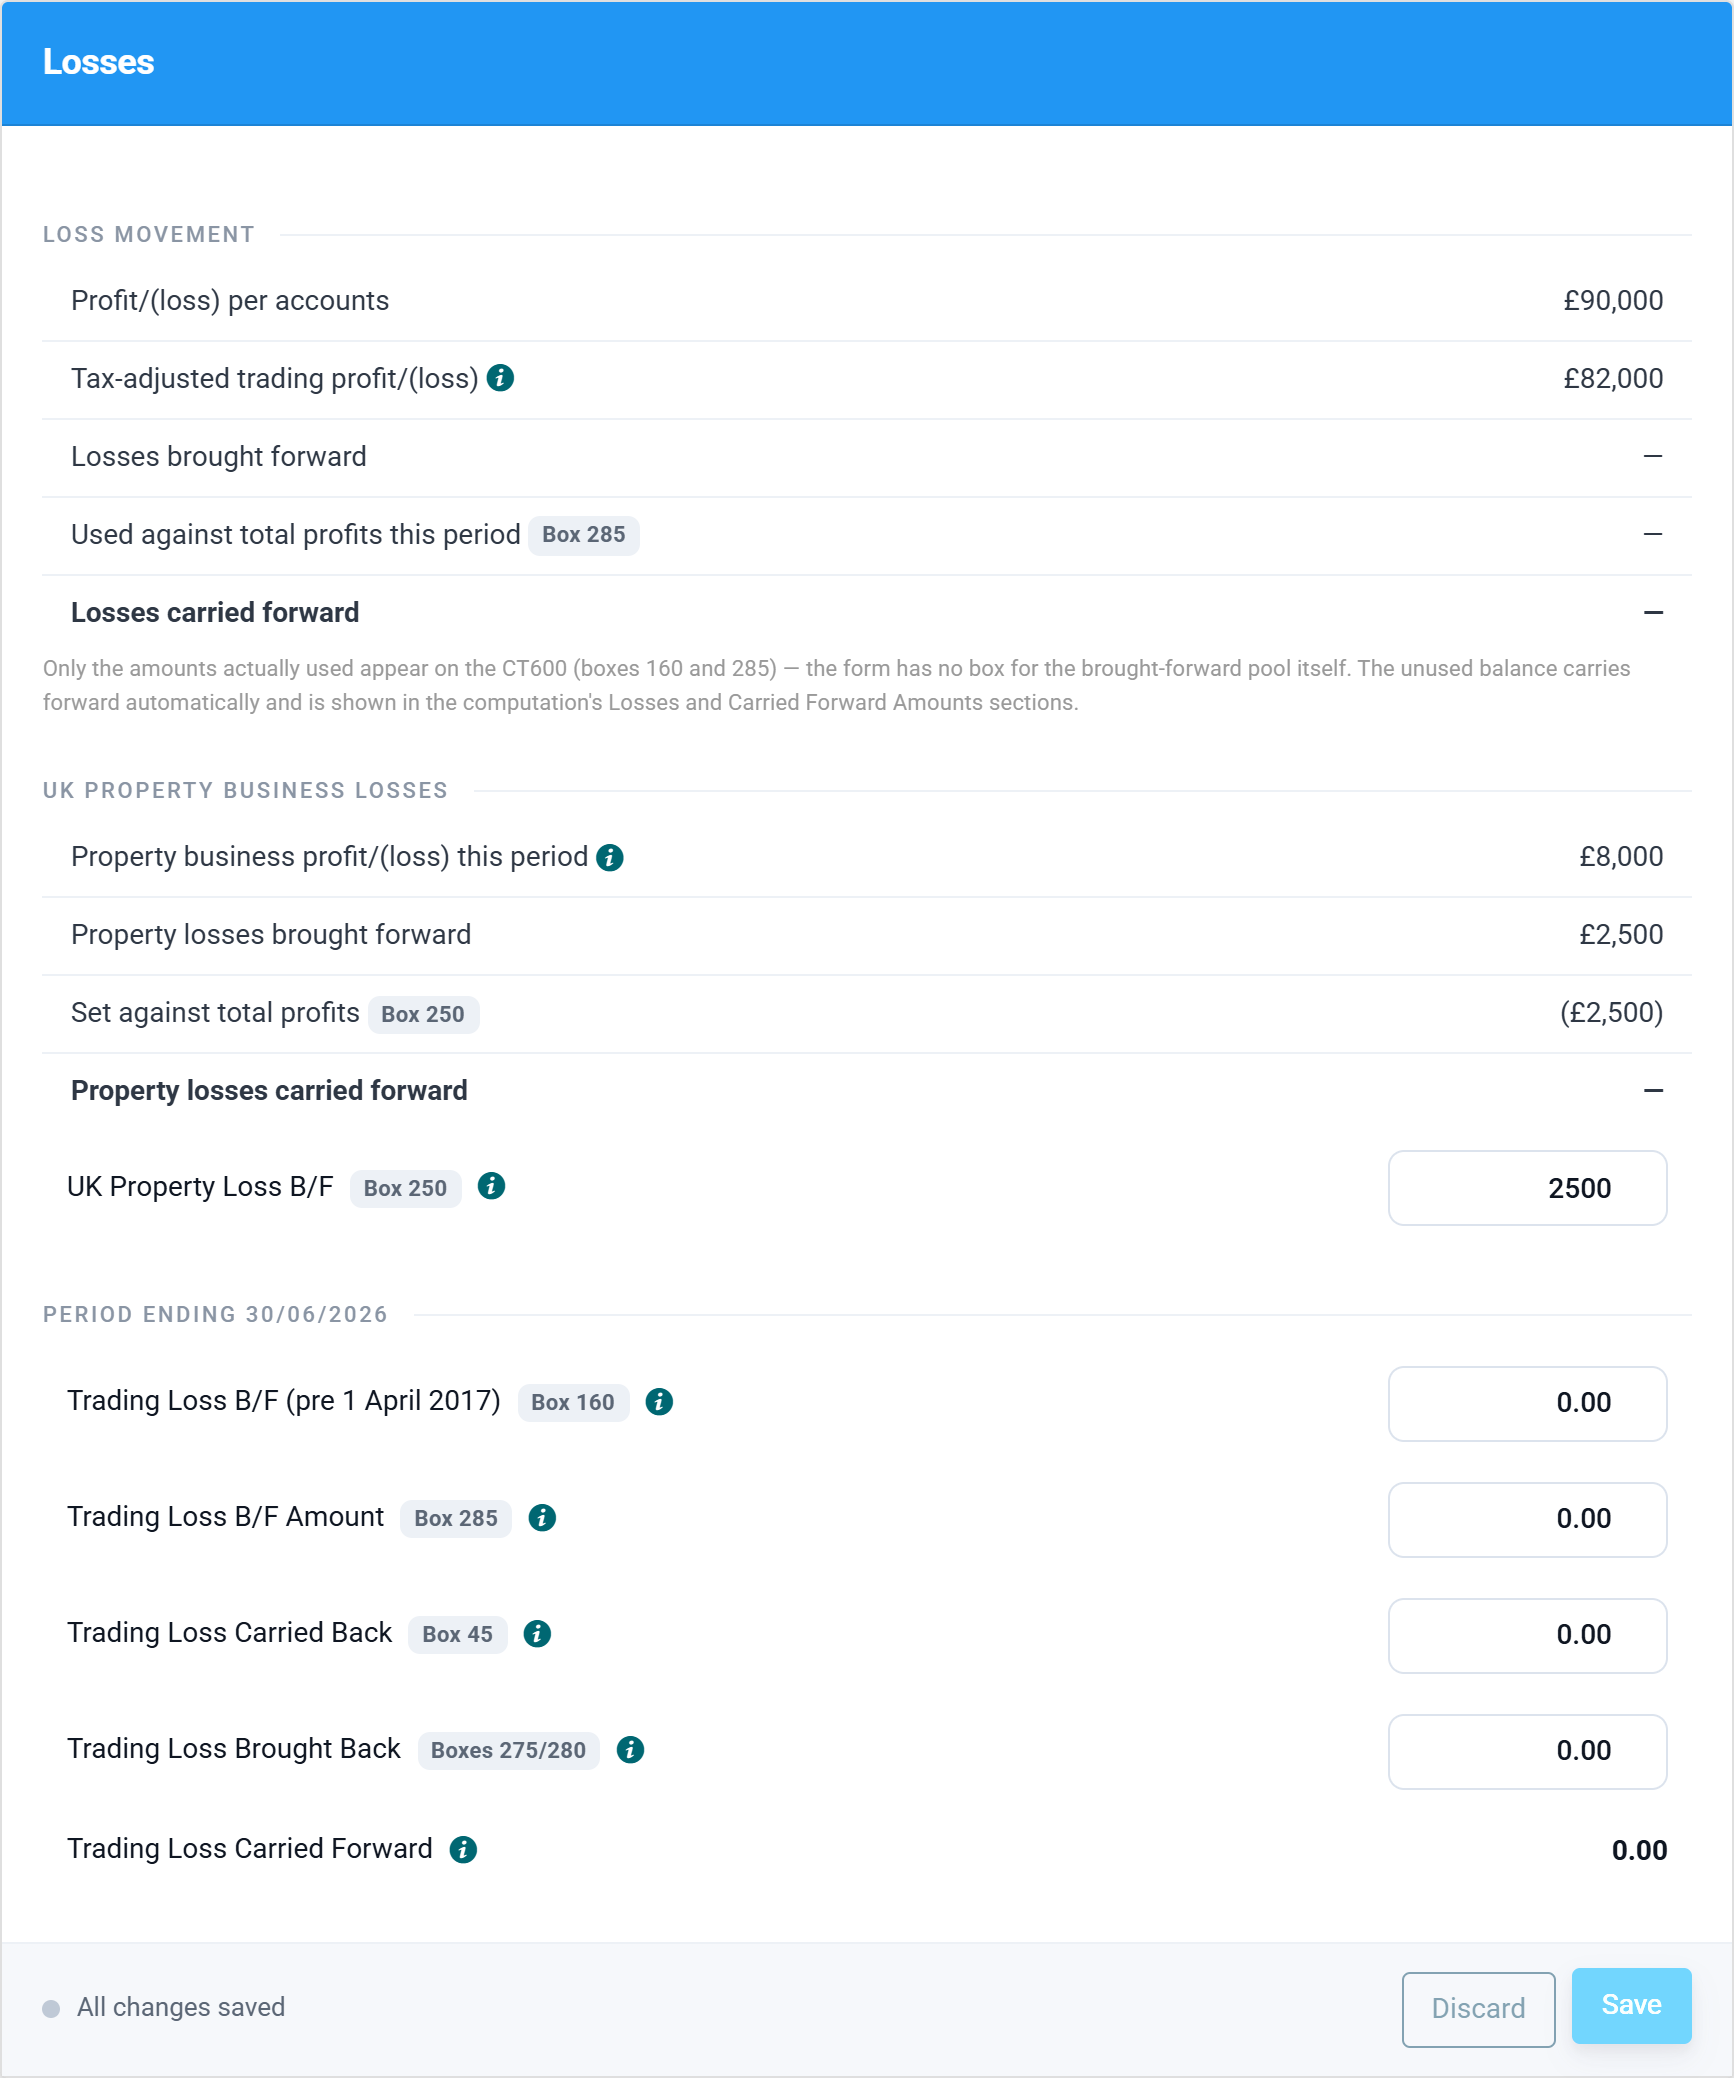
The relief is capped at the profits available, and it ranks before post-2017 trading losses brought forward (box 285) and before charitable donations, so those reliefs see the profit that is left after the property loss. Worked example: trade profit £35,000, rents £8,000, property costs £14,000 — the £6,000 property loss goes in box 805, box 250 relieves £6,000 and profits chargeable are £29,000. With the same trade profit and a £3,000 property profit plus £5,000 of losses brought forward, box 190 shows £3,000, box 250 relieves £5,000 and profits chargeable are £33,000.
Long periods
When the accounts run longer than twelve months and the return is split into two periods, the property result is apportioned to each period by days, each period's loss is relieved against that period's total profits, and any balance unused in Period 1 is brought into Period 2 automatically — there is no separate Period 2 input.
Checking the CT600
The CT600 Boxes section shows the property figures in place: box 190 in Income, box 250 in Deductions and reliefs, and box 805 in Losses, deficits and excess amounts. Each row links back to the section that drives it.
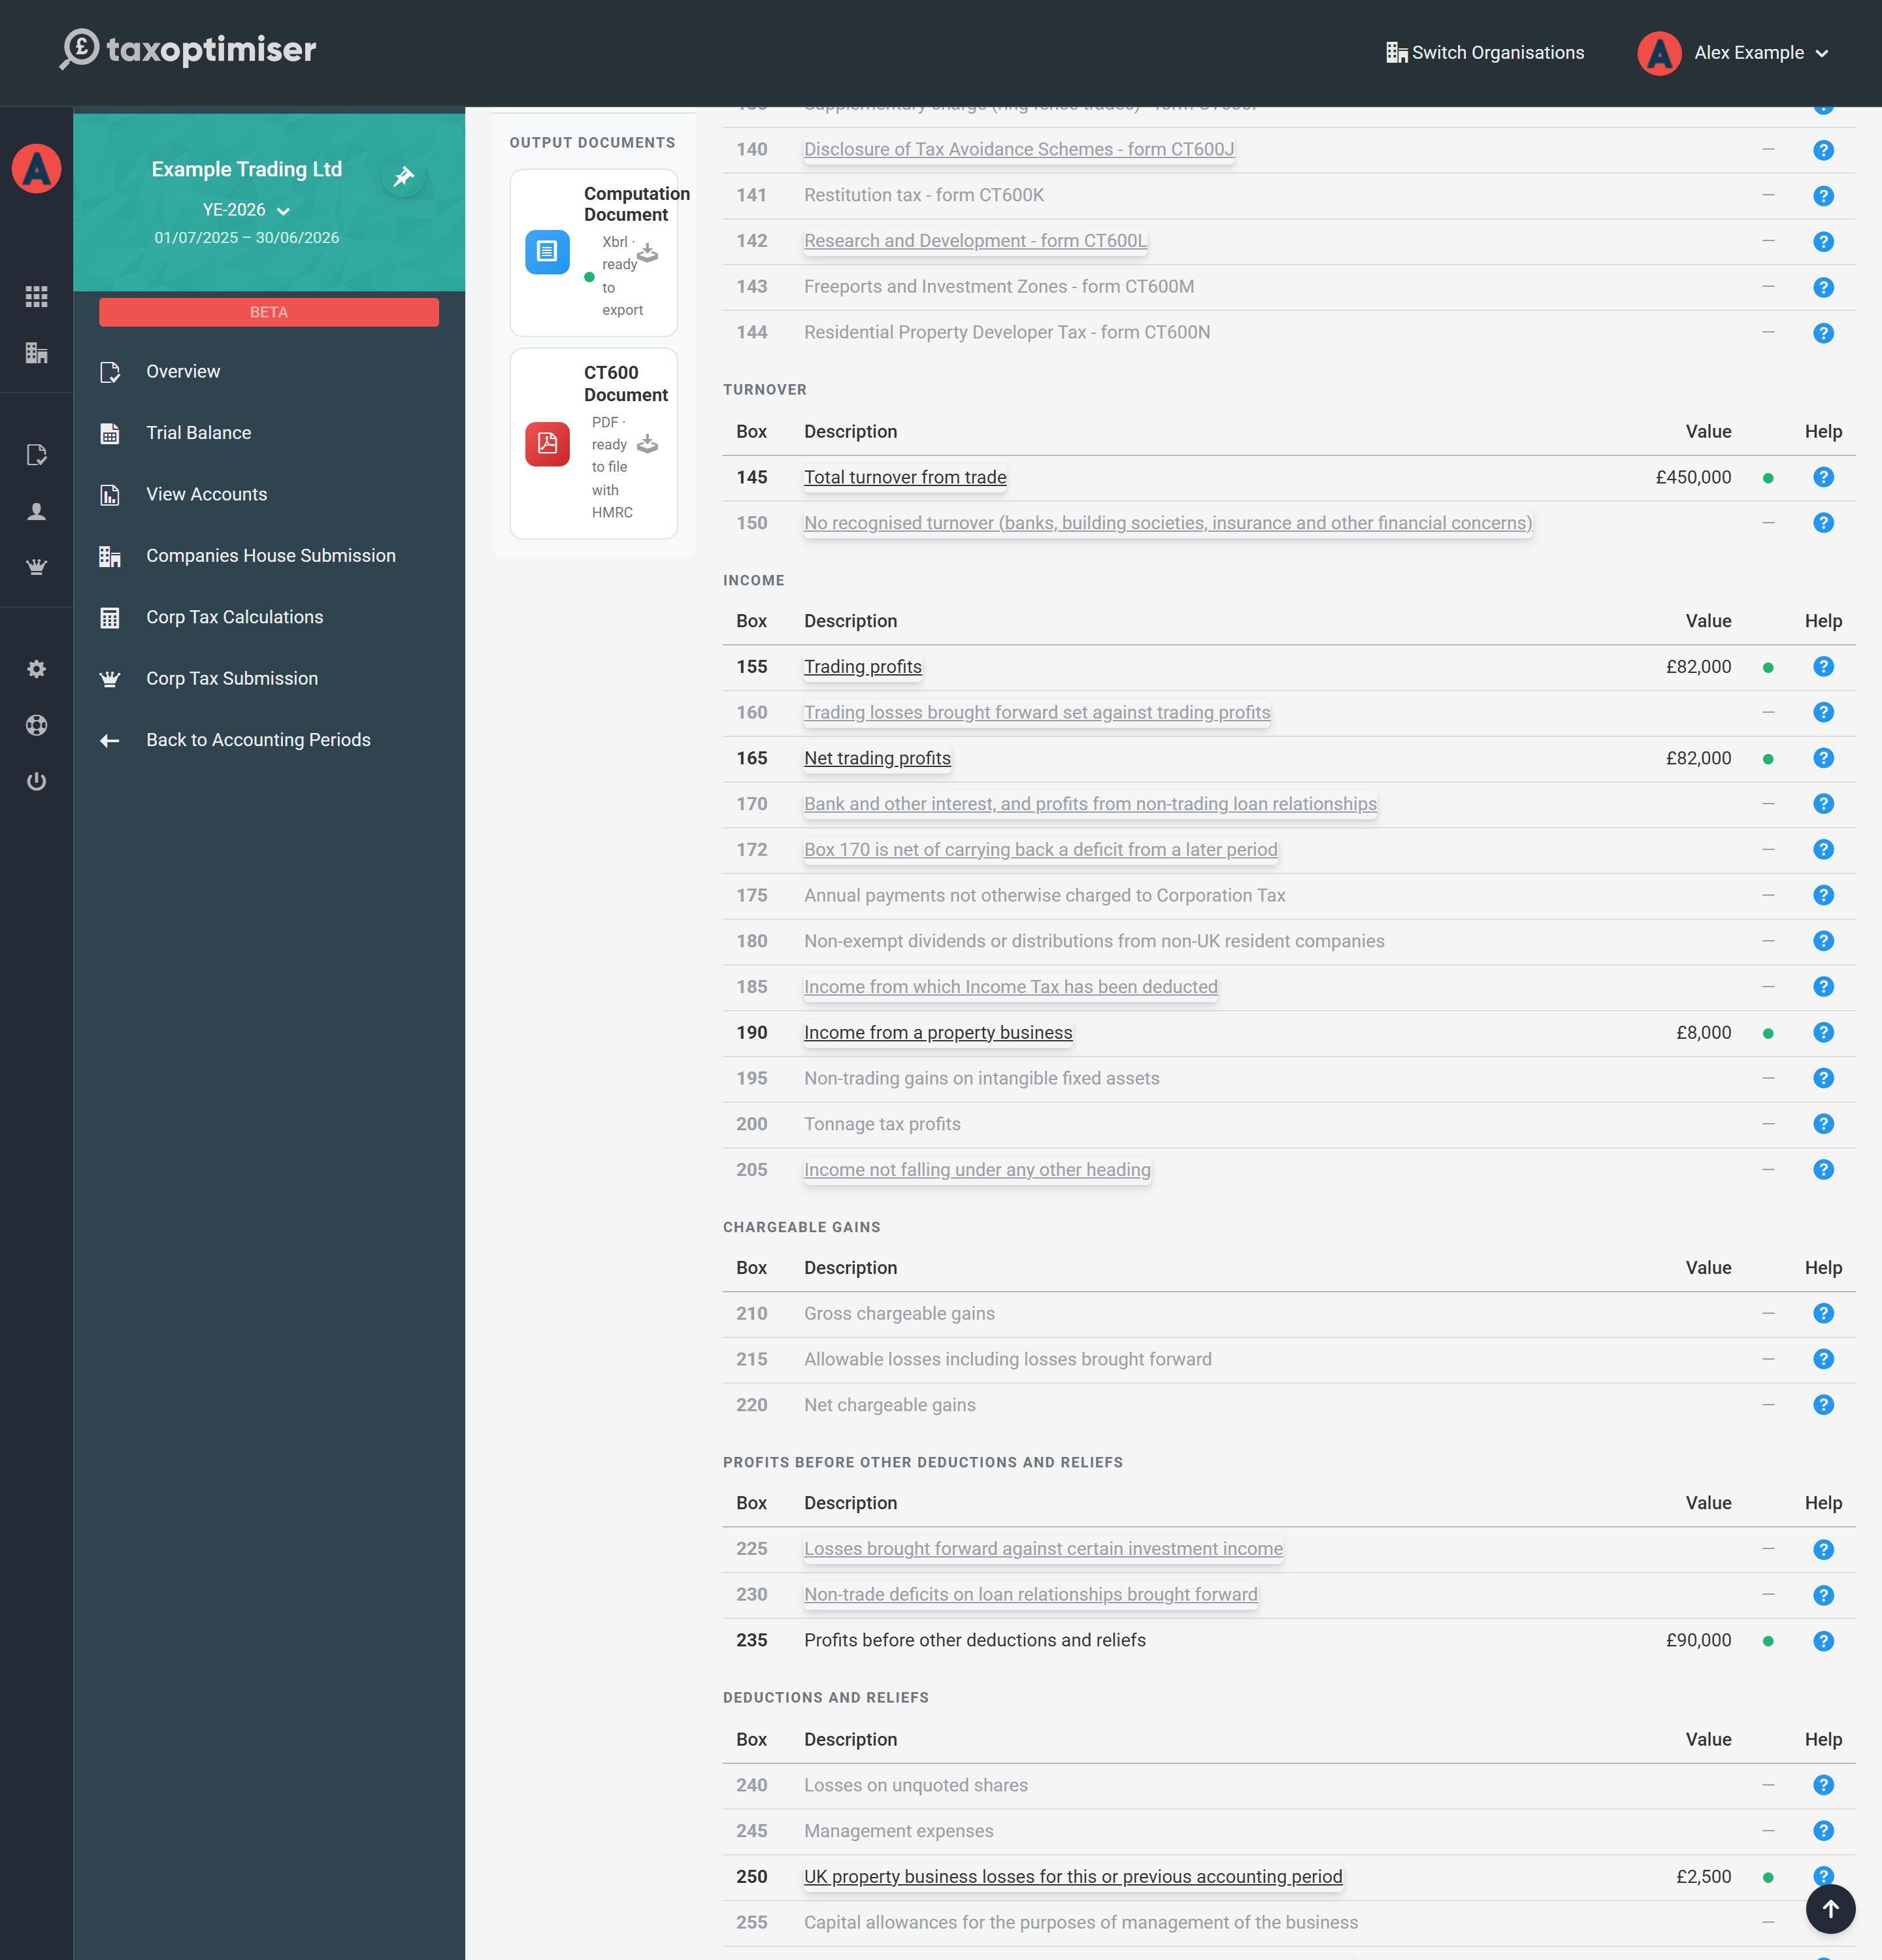
For the official notes see the box 190, box 250 and box 805 entries in the box-by-box guide.
Next: Reviewing the computation, accounts and CT600. Previous: Trading losses: carry forward and carry back.