Most of a company’s income is its trading profit. The rest is taxed under its own heading on the CT600: interest in box 170, rents in box 190, gains in box 220. Three less common kinds of income have boxes of their own too — annual payments (box 175), dividends from overseas companies that are not exempt (box 180) and income received after Income Tax was deducted (box 185). This guide shows where each goes in Tax Optimiser and how they reach the return.
Which box does the income belong in?
- Interest on bank accounts, loans the company has made and other loan relationships belongs on Non Trade Credit (box 170) — even when tax was deducted from it.
- Rents from UK property are a property business (box 190) — see UK property income and losses.
- Dividends from UK companies, and most dividends from overseas companies, are exempt. They are not taxed at all and are recorded on the Investment Income section as exempt distributions (box 620).
- Annual payments not caught by any other heading — for example regular payments under a covenant or deed — go in box 175.
- Dividends from non-UK companies that are not exempt go in box 180.
- Other income received net of basic-rate Income Tax — patent royalties are the usual example — goes in box 185, gross, with the tax deducted in box 515.
- Anything taxable that fits none of these goes in box 205 on the Other Income section.
Step 1: take the income out of the trade
If the receipts are in the company’s accounts, they are in the profit per accounts and so in the trading profit. Tax Optimiser does not know which P&L lines are annual payments or overseas dividends, so take them out of the trade yourself. Open Accounting Adjustment, click Add Income Adjustment and enter the total as both Non-Taxable and P/L Amount.
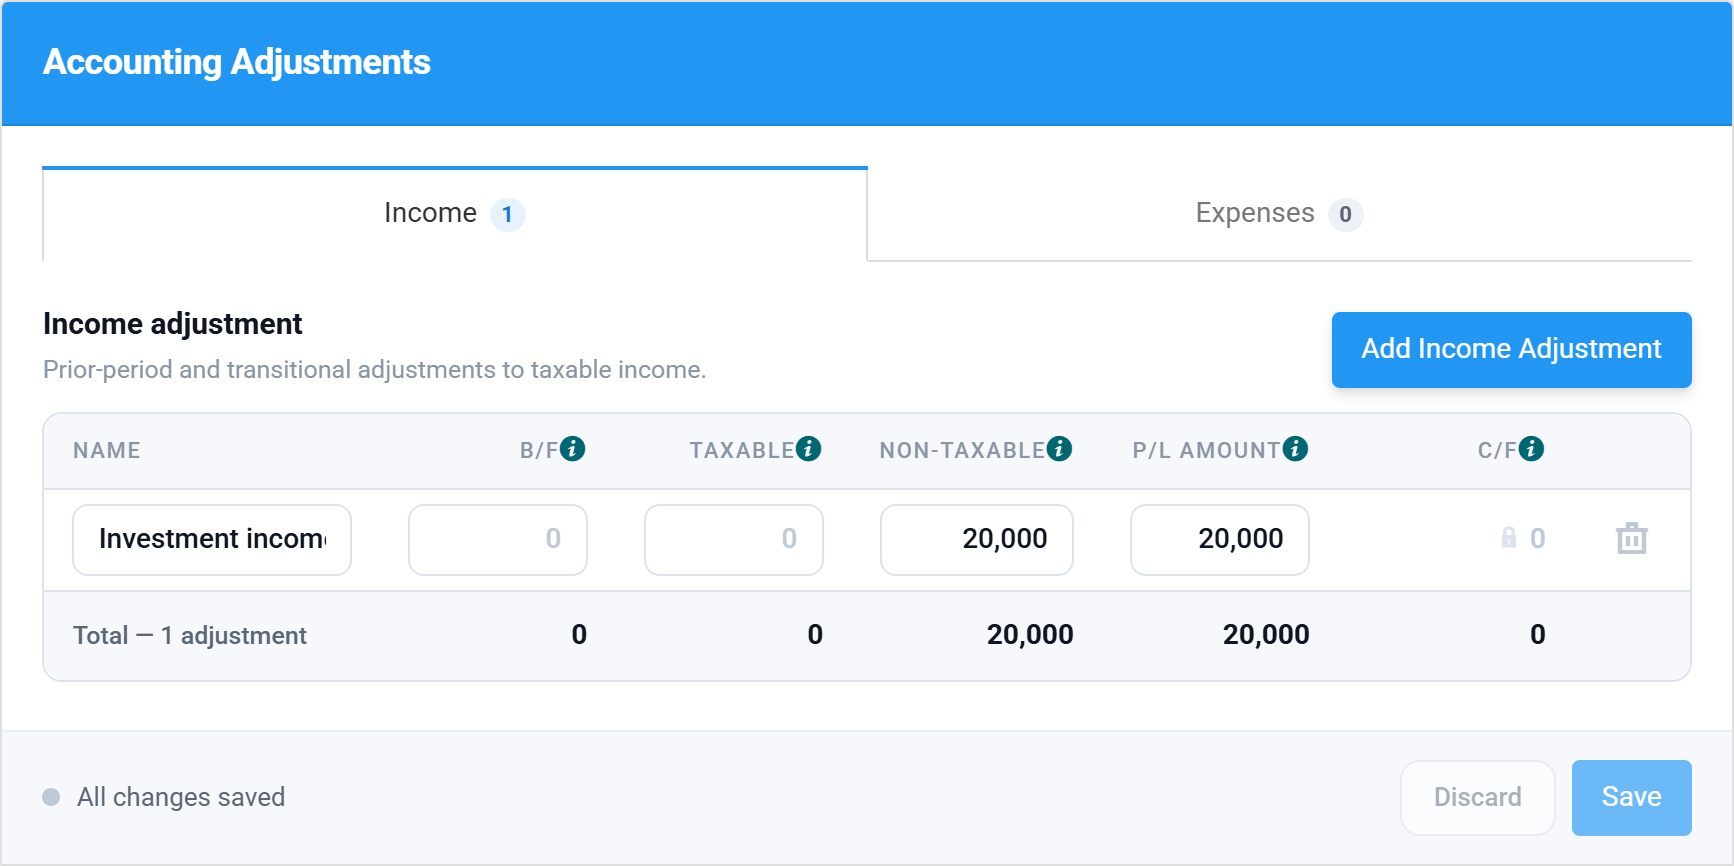
Without this step the income would be taxed twice: once in the trading profit and again in its own box.
Step 2: enter each kind of income
Box 175 — Annual payments not otherwise charged
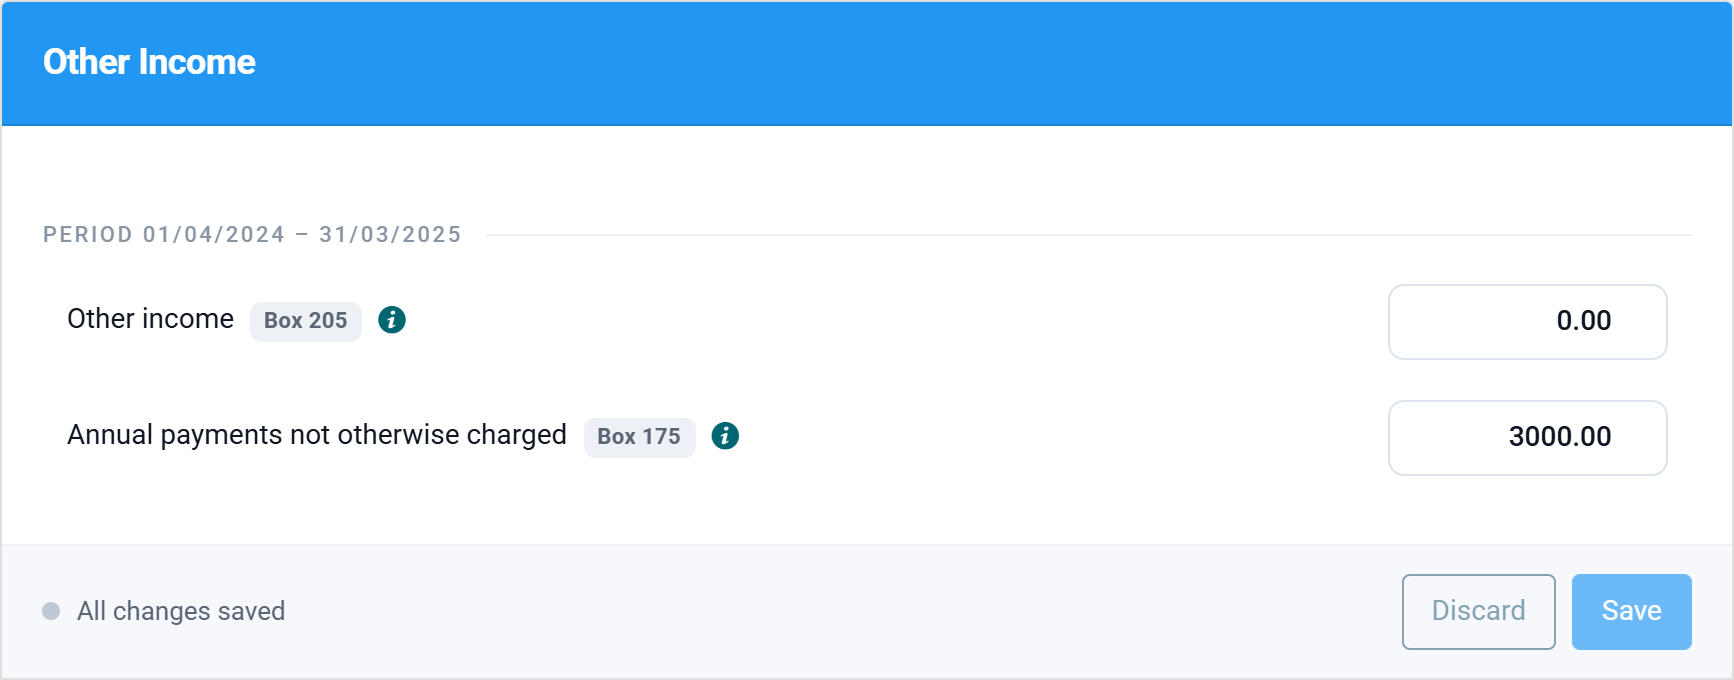
On the Other Income section, enter the full-period figure in Annual payments not otherwise charged. Use it only for payments received without Income Tax deducted; payments received net of tax belong in box 185.
Box 180 — Non-exempt dividends from non-UK resident companies
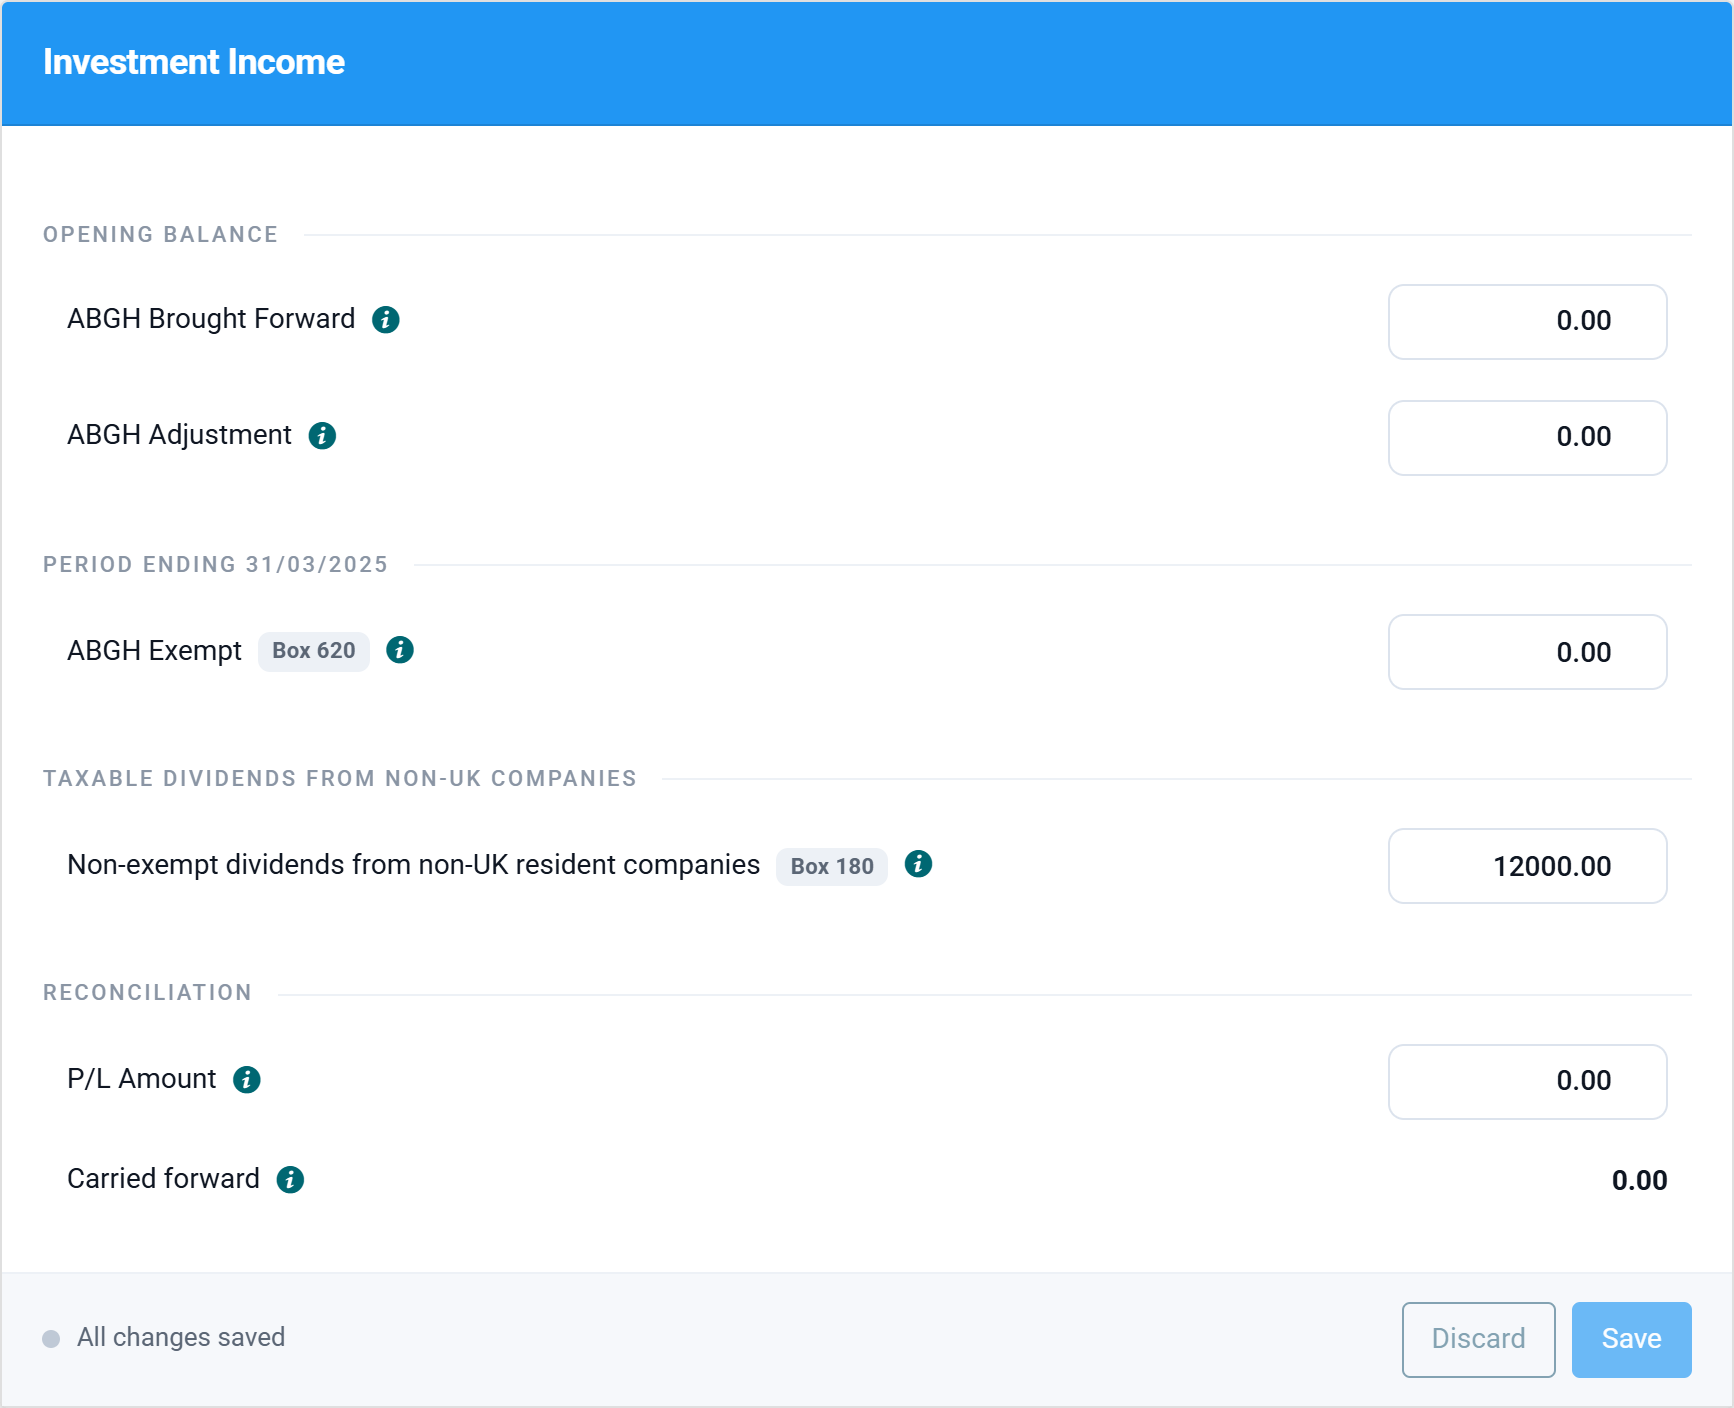
Most dividends a UK company receives are exempt (CTA 2009 Part 9A). A dividend from an overseas company can fall outside the exempt classes — for example a distribution that is deductible for the paying company, or where the company elected for the dividend not to be exempt. On the Investment Income section, enter the gross full-period amount in Non-exempt dividends from non-UK resident companies. If foreign tax was withheld, claim credit for it on the Double Taxation Relief section.
Box 185 — Income from which Income Tax has been deducted
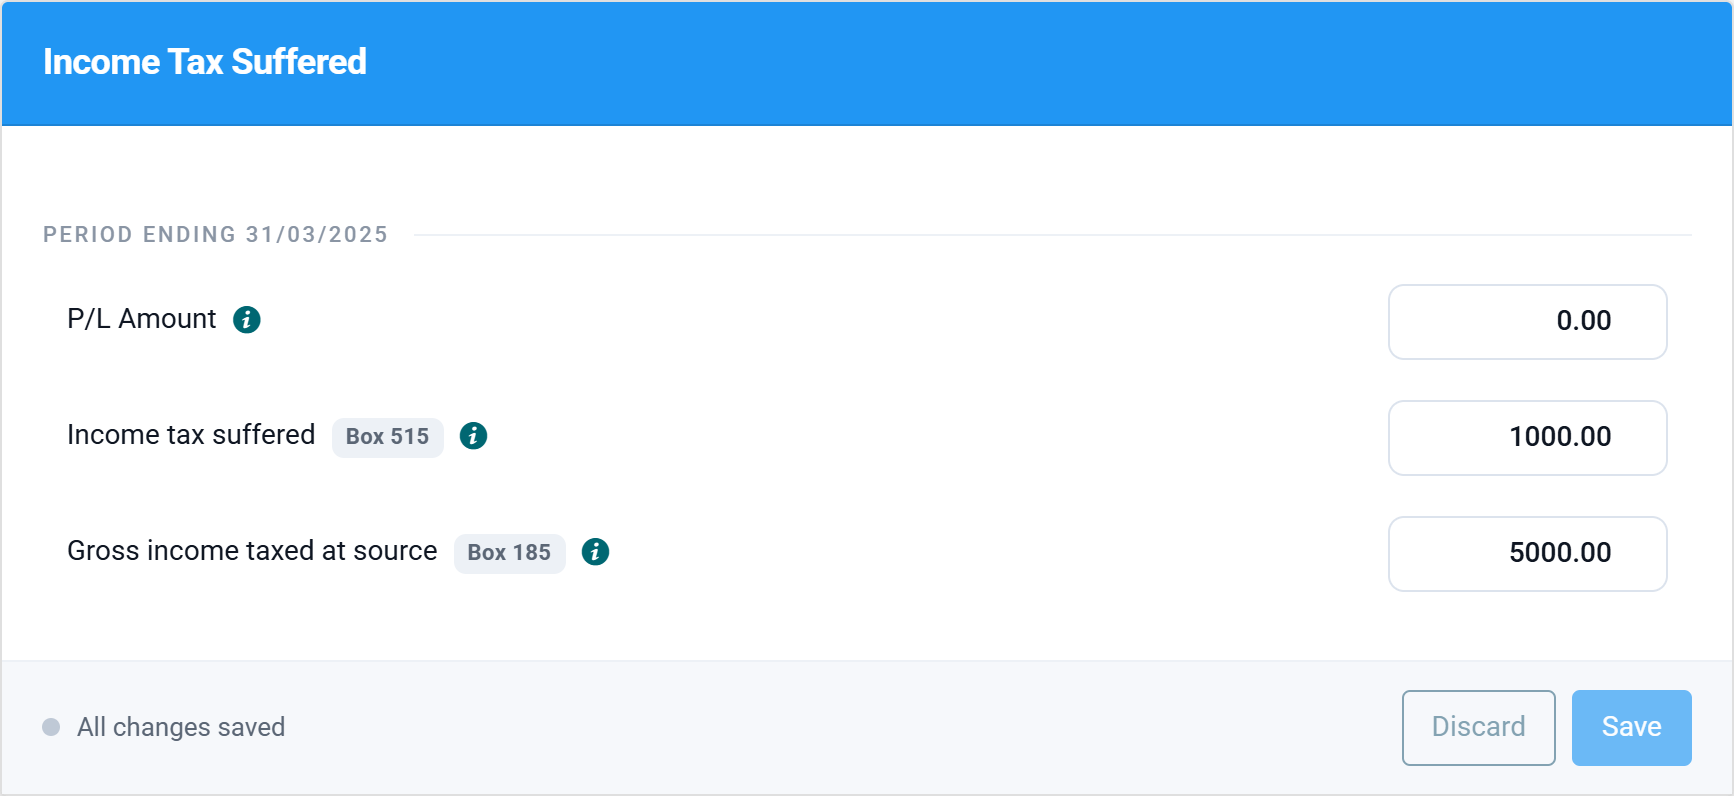
Some payments reach the company with basic-rate Income Tax already taken off — patent royalties paid by an individual, for example. The company is taxed on the gross amount and gets credit for the tax deducted. On the Income Tax Suffered section enter:
- Gross income taxed at source — the amount before the tax was deducted (box 185);
- Income tax suffered — the tax deducted (box 515), which comes off the Corporation Tax payable.
Do not include loan interest here. Interest on the Non Trade Credit section is already in box 170, and its tax deducted is entered in that grid’s Income Tax column.
A worked example
Example Income Streams Ltd, year ended 31 March 2025, has a profit per accounts of £250,000. That includes £20,000 of investment income:
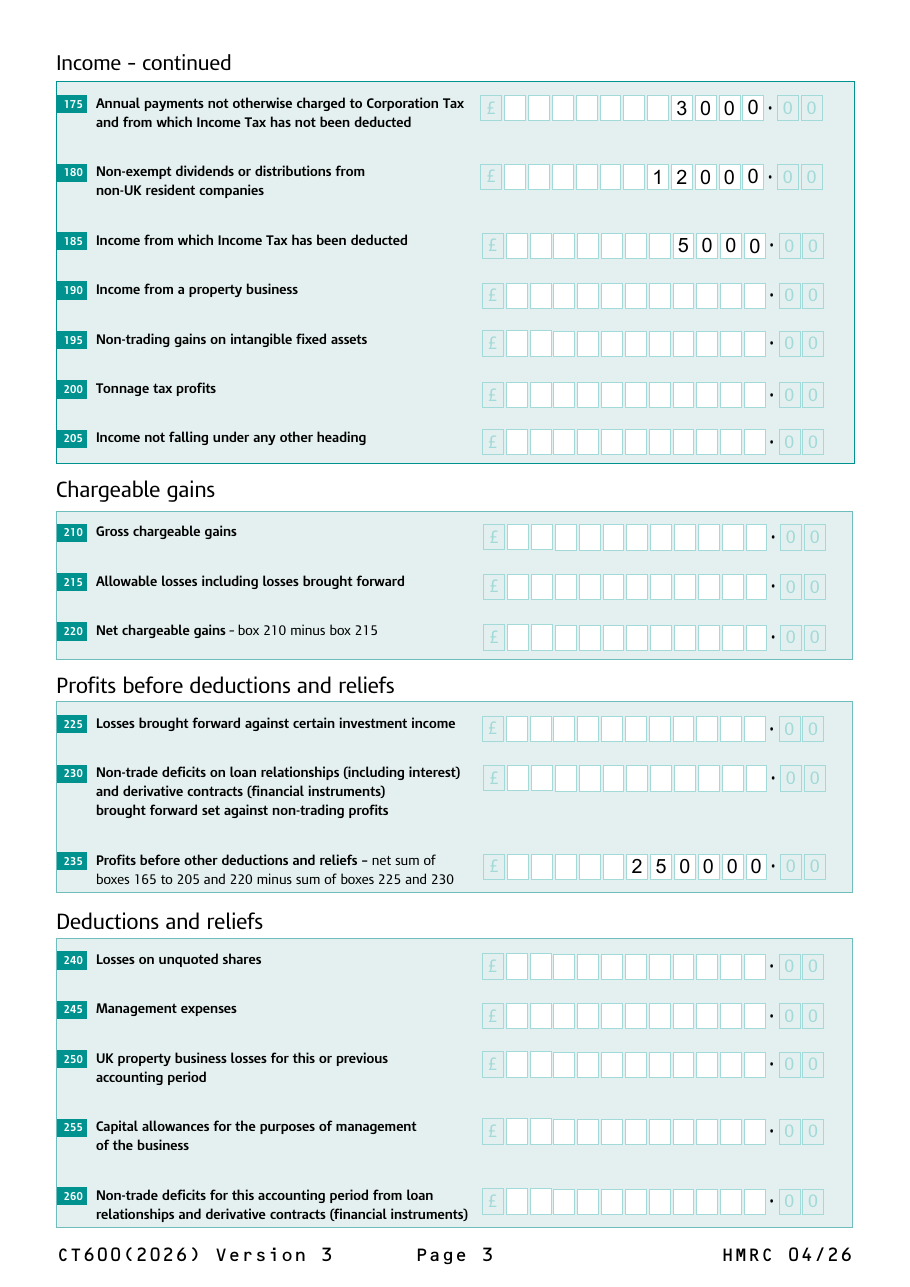
- £3,000 under a covenant, received without deduction (box 175);
- a £12,000 dividend from a US company that is not exempt (box 180);
- £5,000 of patent royalties, received as £4,000 after £1,000 of Income Tax was deducted (box 185 and box 515).
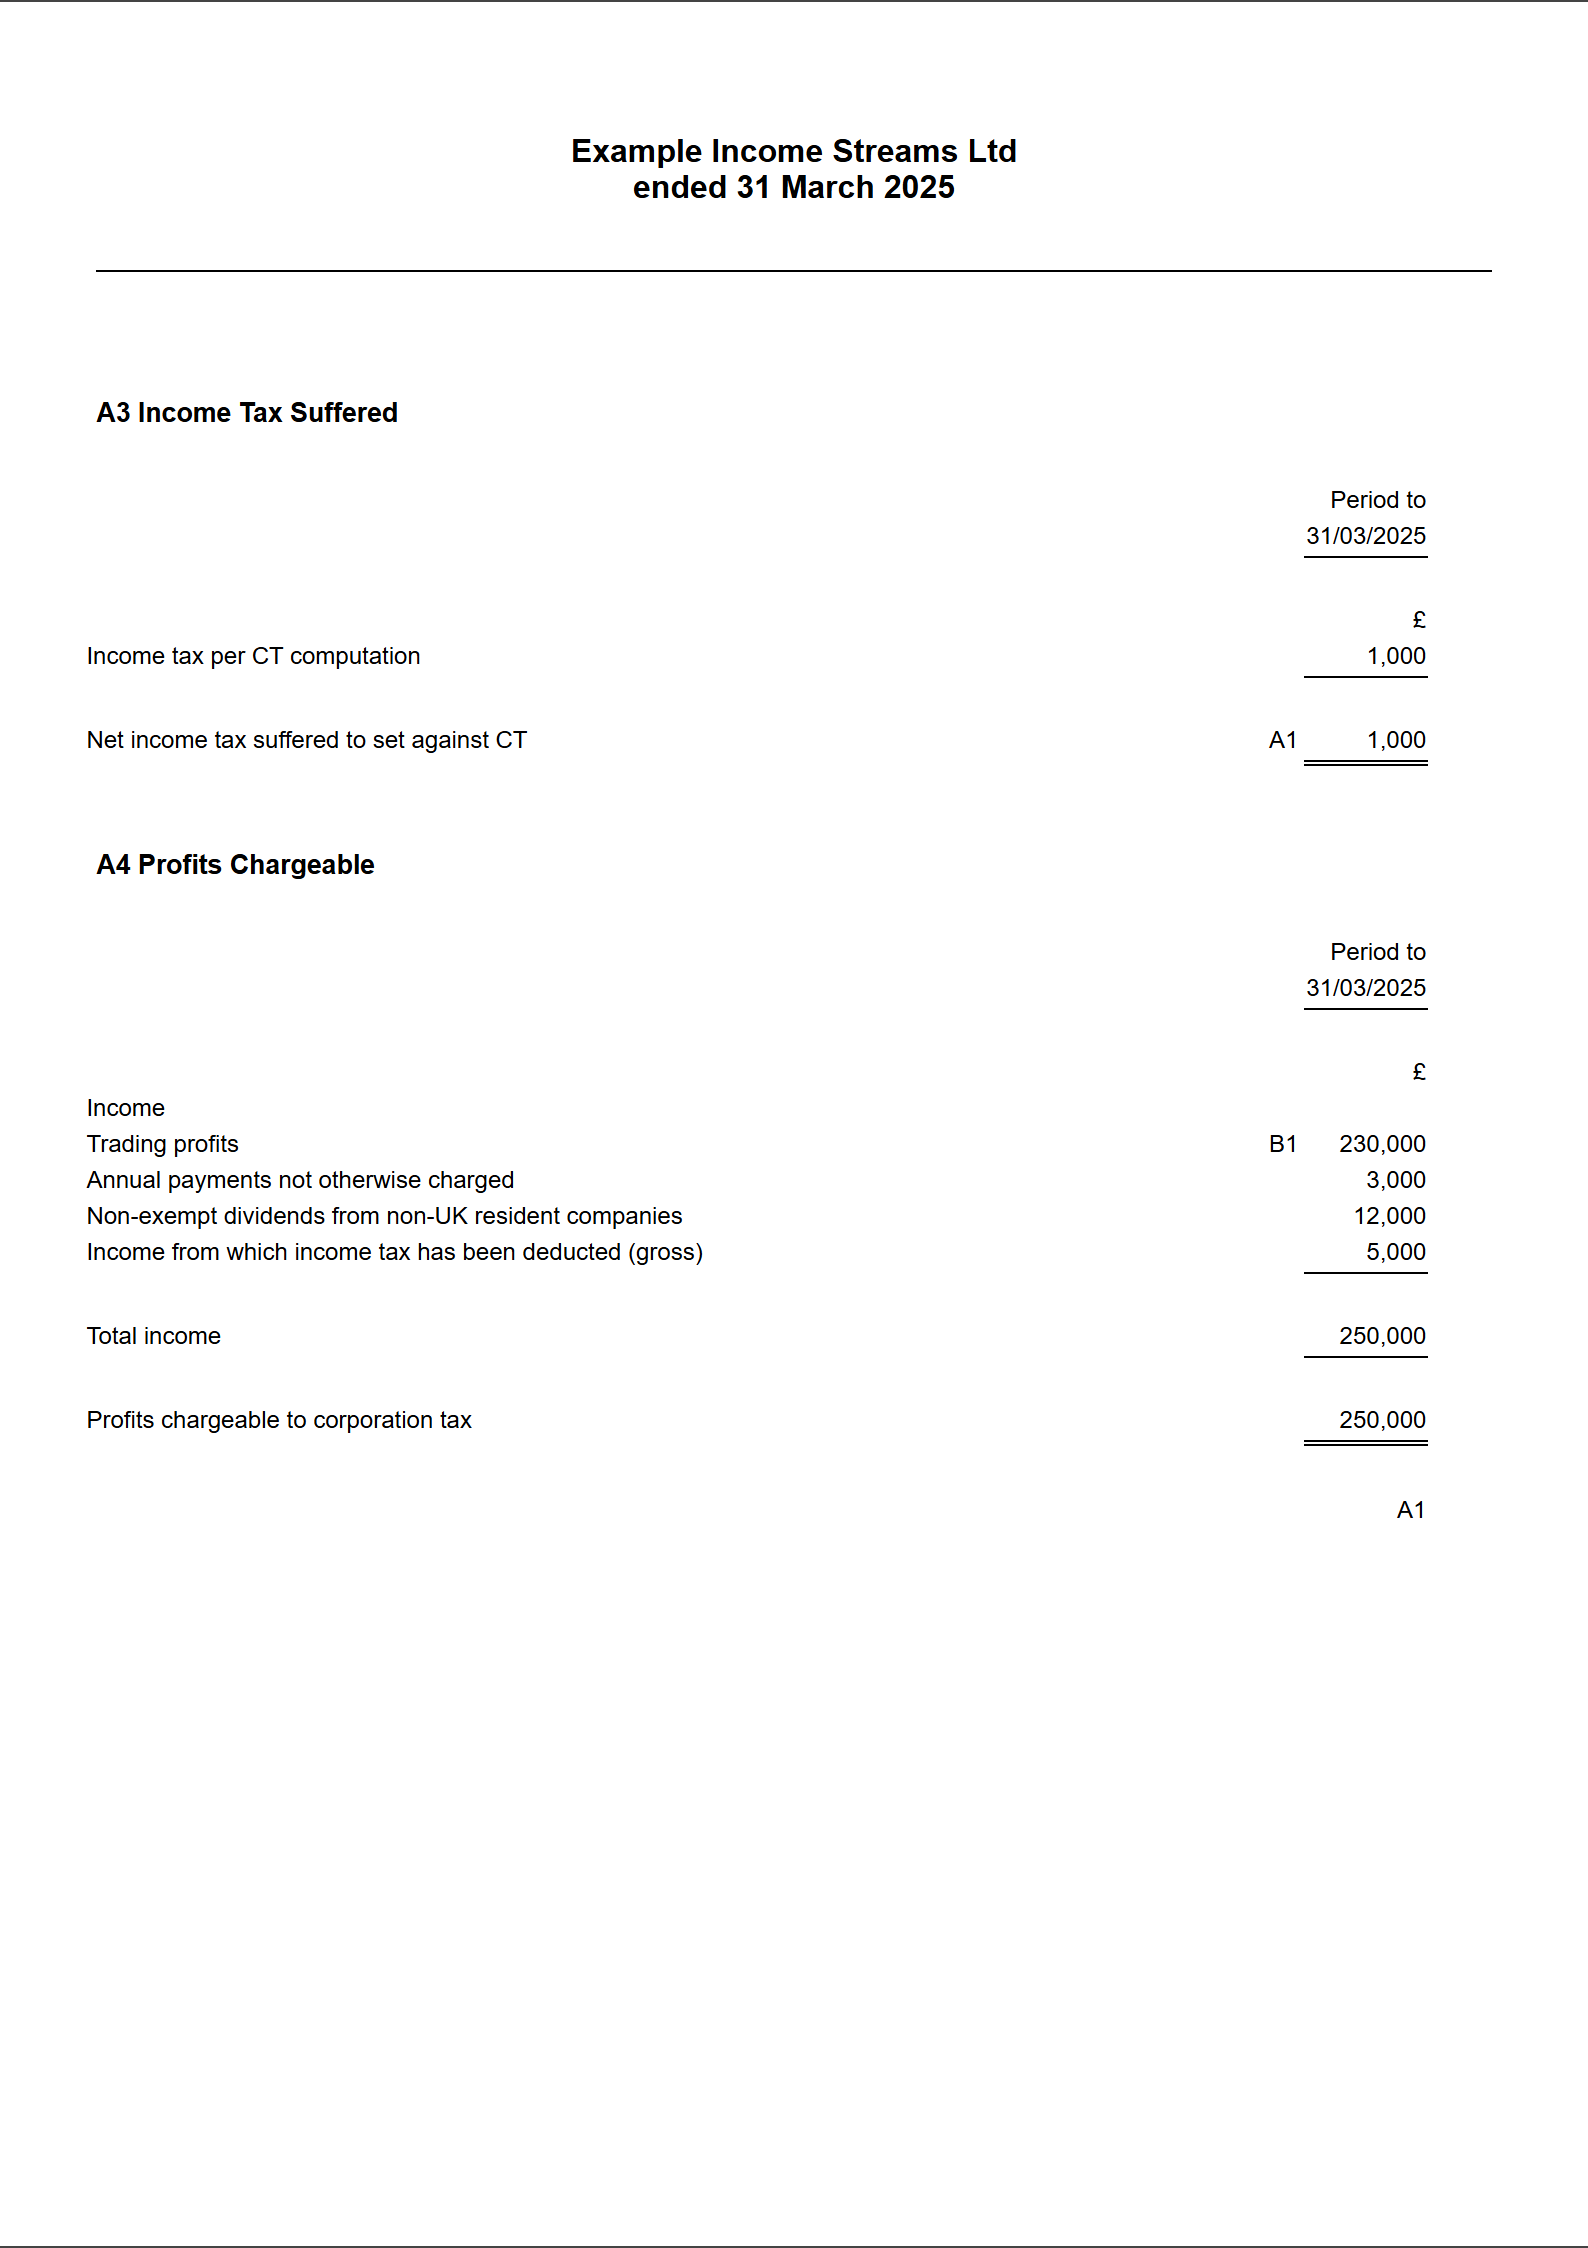
The Income adjustment brings the trading profit down to £230,000. The three income heads add £20,000 back, so box 235 is £250,000. Tax at 25% is £62,500, less the £1,000 of Income Tax suffered: Corp Tax Payable is £61,500.
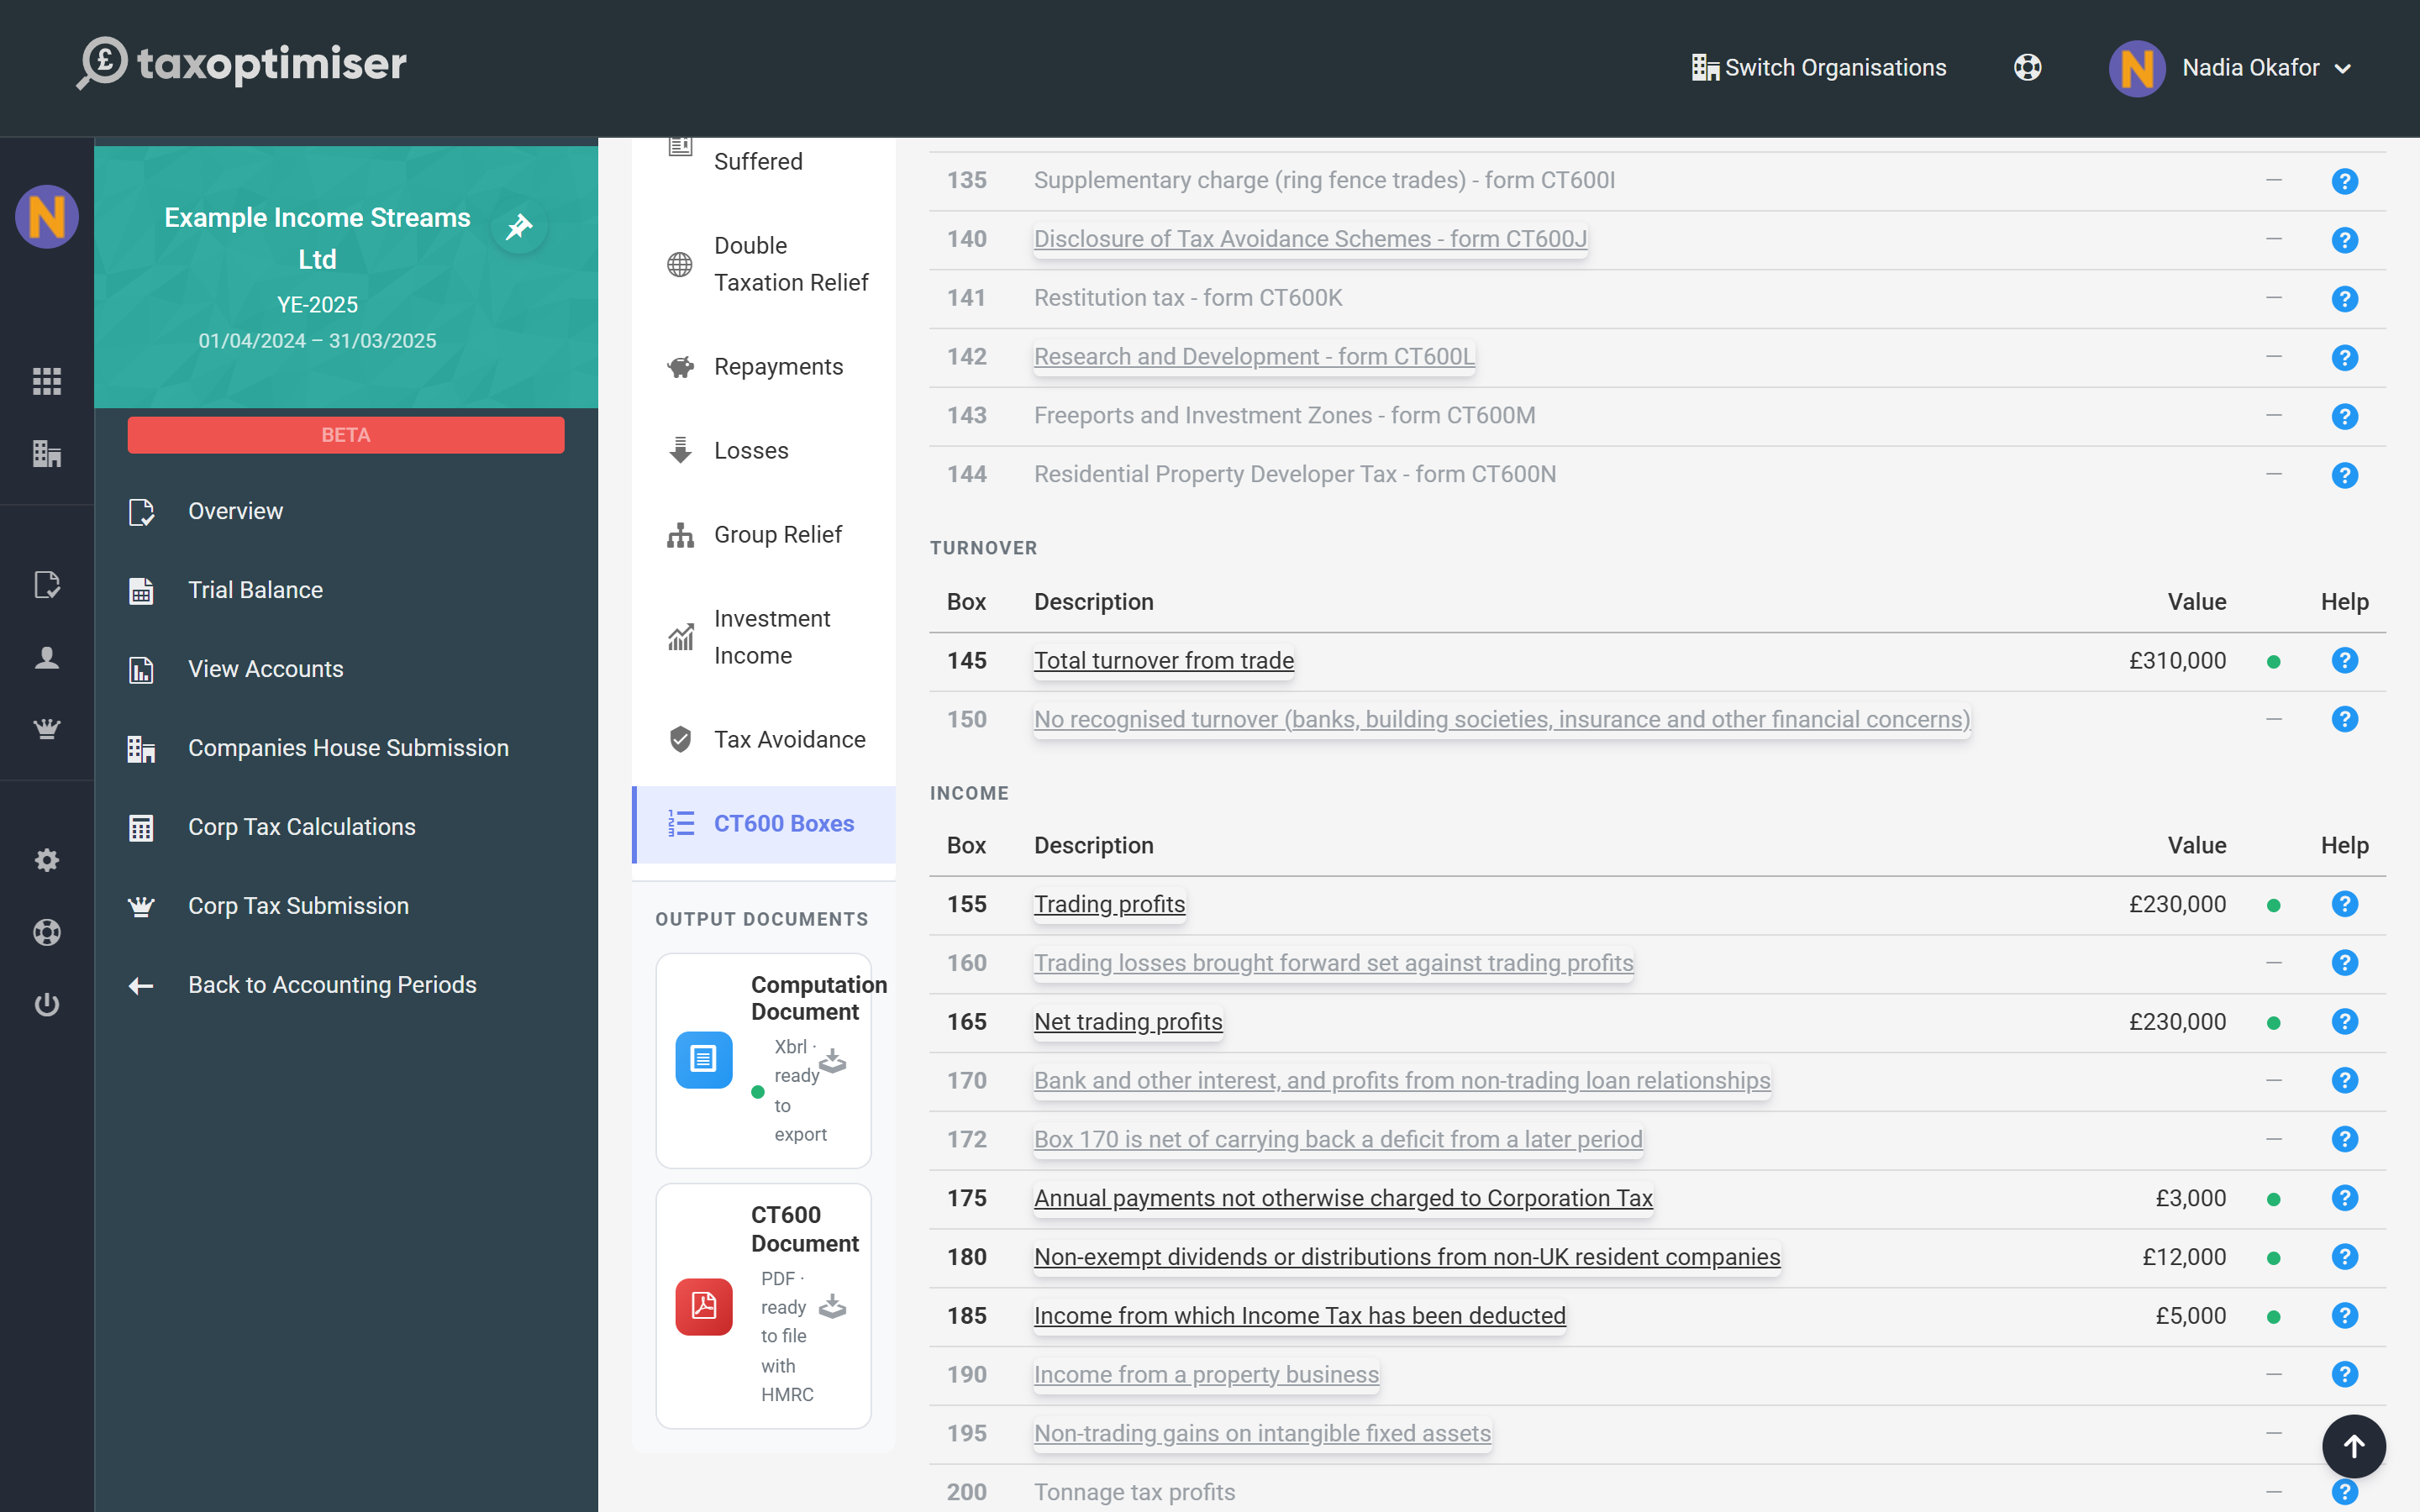
The computation lists each head under Income, and the CT600 carries them on page 3.
Long periods and charities
When the accounts run for more than twelve months the return is split in two. Annual payments and non-exempt dividends are entered once for the whole period and shared between the two returns by days. Income taxed at source is entered for each return period, alongside the Income Tax suffered.
A charity or CASC claiming exemption on all its income on the CT600E has none of these amounts charged: the boxes stay blank.
CT600 boxes
The three boxes are described in the steps above: box 175, box 180 and box 185.
Box 235 — Profits before other deductions and reliefs
The sum of boxes 165 to 205 — including boxes 175, 180 and 185 — plus box 220, less boxes 225 and 230. Calculated automatically.
Box 515 — Income Tax deducted from gross income
The Income Tax suffered entered on the Income Tax Suffered section, plus the tax entered on Non Trade Credit rows. It comes off the Corporation Tax payable and can be repaid if it is more than the tax.
Frequently asked questions
Where do I put dividends a company receives from overseas?
Most are exempt, so they are not taxed and go on the Investment Income section as exempt distributions (box 620). Only dividends outside the exempt classes go in box 180, as Non-exempt dividends from non-UK resident companies.
What is box 185 on the CT600?
The gross amount of income the company received after Income Tax had been deducted, such as patent royalties. The tax deducted goes in box 515 and is credited against the Corporation Tax.
Does bank interest go in box 185?
No. Interest is a loan relationship credit and goes in box 170 through the Non Trade Credit section, even when tax was deducted from it.
What counts as an annual payment for box 175?
Recurring payments the company is entitled to that are pure income and not taxed under another heading, such as payments under a covenant, received without Income Tax deducted.
Why do I need an Income adjustment?
The receipts are already in the profit per accounts. Taking them out of the trade with an Income adjustment stops them being taxed twice, once in the trading profit and again in their own box.
Where to go next
- Building the Corporation Tax computation — the other sections of Corp Tax Calculations.
- Intangibles and other reliefs on the CT600 — boxes 195, 265 and 290.
- CT600 box-by-box guide — every box on the main return.